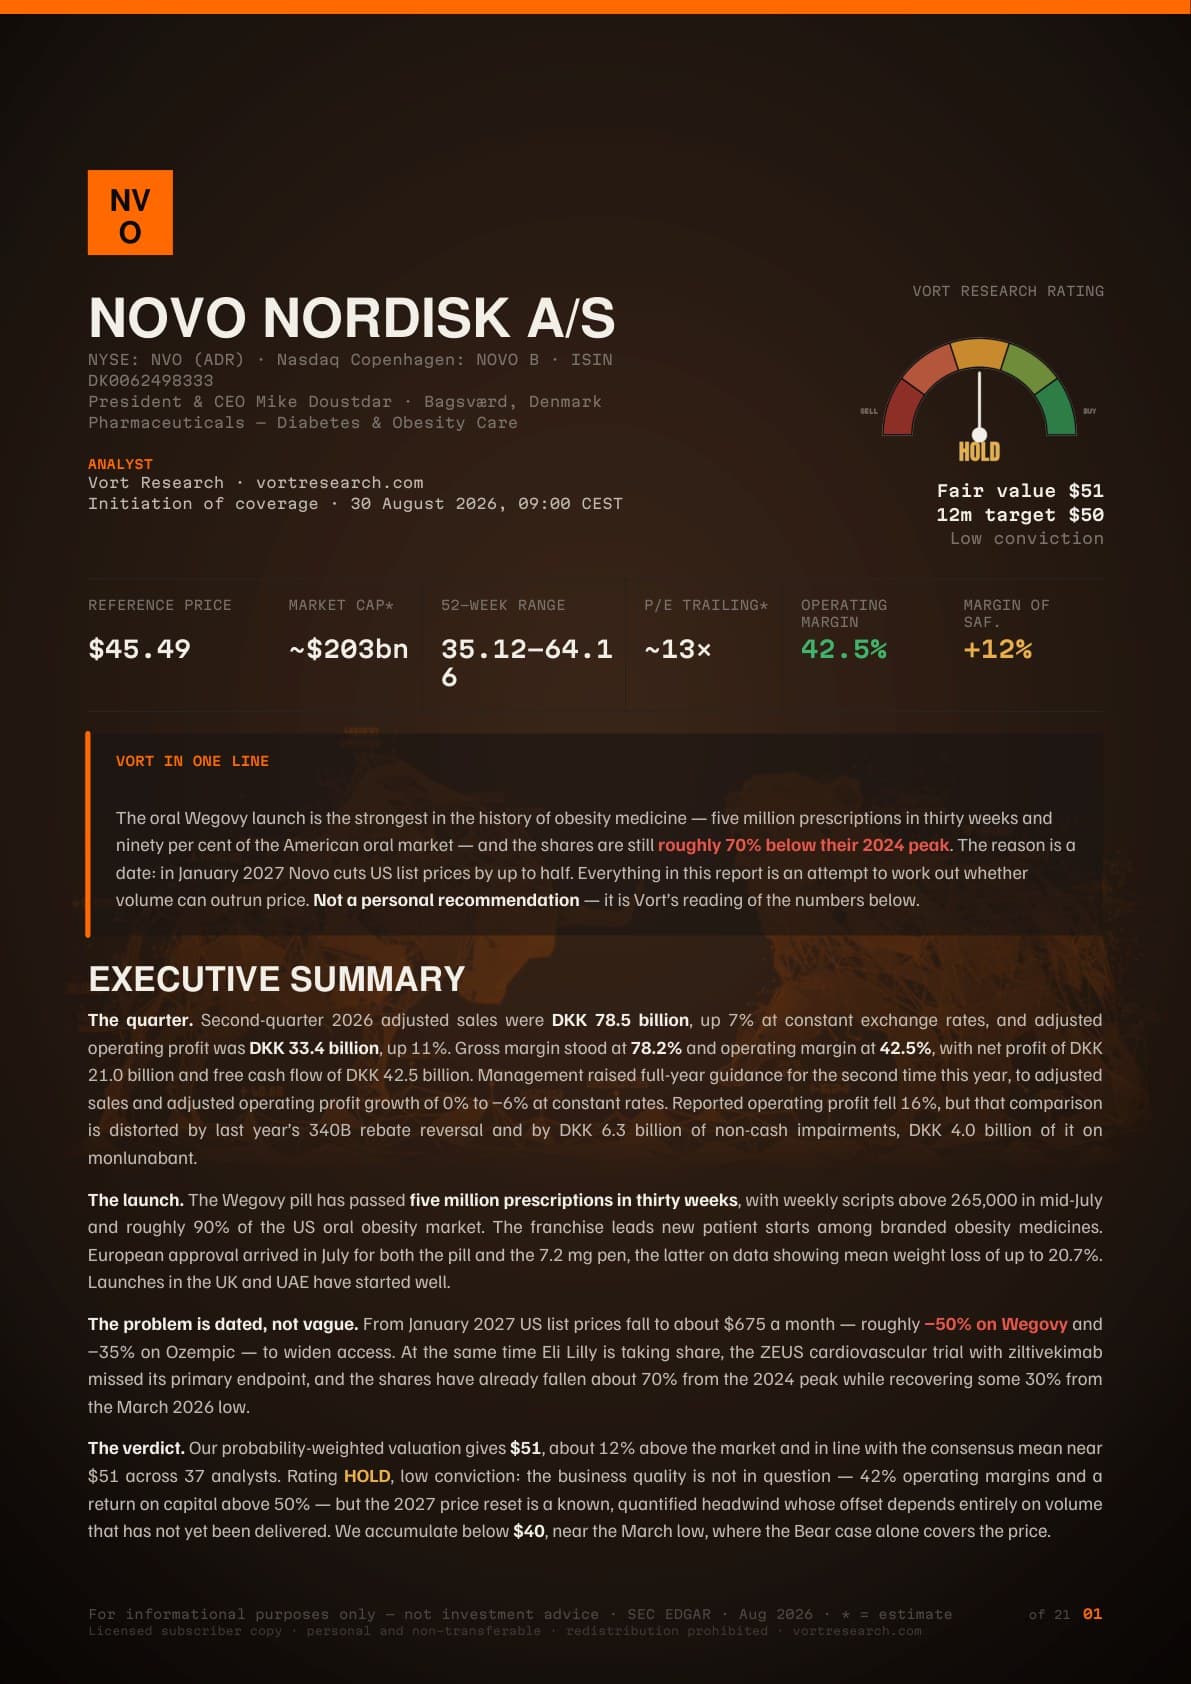
The oral Wegovy launch is the strongest obesity medicine has seen — five million prescriptions in thirty weeks and ninety per cent of the US oral market — and the shares still sit some 70% below their 2024 peak. In January Novo cuts its own American list prices by up to half. Everything here is an attempt to work out whether volume can outrun price.
The US market is closed: the price is the close of October 15, 2026. During the session the quote is delayed up to 15 minutes. The fair value is the report’s, dated August 30, 2026; it does not move with the market. Vort Research provides informational and educational content. It is not personalised financial advice nor a solicitation to invest.
The full report is for Vort+ members.
The rating, the fair value and the reasoning on this page are public. The PDF and the slides download with Vort+; if you already have it, sign in.
The Wegovy pill has passed five million prescriptions in thirty weeks, with weekly scripts above 265,000 in mid-July and roughly 90% of the US oral obesity market. The franchise leads new patient starts among branded obesity medicines, and European approval arrived in July for both the pill and the 7.2 mg pen.
The problem is dated, not vague.
From January 2027 US list prices fall to about $675 a month — roughly −50% on Wegovy and −35% on Ozempic. At a 78% gross margin and a 42.5% operating margin, price passes almost undiluted into profit, in either direction.
Same number as the market, less conviction.
Our probability-weighted valuation gives $51, in line with the consensus mean across 37 analysts — and we call it a hold where two thirds of them call it a buy. A 12% gap does not cover a variable that resets in January.
pill scripts in 30 weeks
>5m
of the US oral obesity market
~90%
operating margin, Q2
42.5%
from the 2024 peak
~−70%
The accounts in brief
Second quarter 2026, reported 4 August
Adjusted sales, Q2
DKK 78.5bn
↗ rising: +7% CER
Adjusted operating profit, Q2
DKK 33.4bn
↗ rising: +11% CER
Reported operating profit
—
↘ falling: −16%
Net profit, Q2
DKK 21.0bn
Free cash flow, Q2
DKK 42.5bn
Gross margin, Q2
78.2%
Sales FY26E
~DKK 308bn
↘ falling: 0 to −6%
Return on capital
~53%
The analysis
Free summary
Why a price cut lands so hard here
Gross margin runs near 78% and operating margin above 42%, because the cost of goods on a peptide is small relative to the price. At these margins a change in price passes almost undiluted into profit, in either direction. That single fact is why the pricing question dominates everything else in the file.
The pill is not only convenience
An oral formulation widens the addressable population — patients who will not inject — and management now says openly it can see a future in which this is largely a pill market. The catch is arithmetic: oral semaglutide needs substantially more active ingredient per patient, because absorption through the gut is inefficient.
What a duopoly does to price
Two well-capitalised firms with similar products and enormous capacity do not compete on science for long; they compete on access, and access is bought with price. That dynamic, more than any single trial result, is what has taken 70% off this share price.
We do not disagree with the market about what Novo Nordisk is worth. We disagree about how much confidence that number deserves.
Vort Research — Novo Nordisk initiation, 30 August 2026
What it does, and how it earns
The business
Novo Nordisk treats metabolic disease. It is a Danish company that has spent a century in insulin and the last five years discovering that the same class of molecules — GLP-1 receptor agonists — treats obesity. Semaglutide is sold as Ozempic for type 2 diabetes and as Wegovy for weight management; more than 46 million people are treated with the company’s diabetes and obesity products.
Where the revenue comes from
Wegovy pill — oral, daily–share not given
Wegovy injectable — weekly pen–share not given
Ozempic — type 2 diabetes–share not given
Rybelsus — oral, daily–share not given
Rare disease — haemophilia and other–share not given
The model
The report does not break sales down by product, so no split is shown here. What matters structurally is that supplier power is low — peptide manufacturing is in-house and capacity is built — while buyer power is very high: American payers, pharmacy benefit managers and now the federal government set the price at which the medicine reaches patients.
The Vort verdict in four lines
This is a qualitative summary and not a recommendation.
Business
✓Very strong
42.5% operating margin and a return on capital near 53%, after a 70% de-rating.
The launch
✓Exceptional
Five million prescriptions in thirty weeks and about 90% of the US oral market.
Pricing
×The whole question
US list prices fall to $675 a month from January 2027, roughly half on Wegovy.
Valuation
±Fair, not cheap
About 13x — but the market is valuing 2027, after a cut already announced.
Who it competes with
Company
Where it competes
Novo NordiskThis stock
Semaglutide: Ozempic, Wegovy and the Wegovy pill
Eli Lilly
Tirzepatide and Foundayo — larger, growing, guides to $85–87bn
Amgen, Roche, Pfizer
Next-generation obesity in phase 2/3, later to market
Compounded semaglutide
The US cash-pay channel — suppressed but persistent
Chinese biosimilars
International markets; semaglutide patents expire from 2026
This is a duopoly at the top, and that is the problem rather than the comfort. Lilly is the larger company and, on 2026 guidance, growing while Novo contracts. Novo’s answer has been speed on formulation: the Wegovy pill reached the US market roughly four months before Foundayo, and that head start is visible in the prescription data.
How we value it
The number and the reasoning
Vort fair value
$51
A probability-weighted valuation on 2027 earnings against an exit multiple, not a discounted cash flow: Bear $32 at 35%, Base $54 at 50%, Bull $84 at 15%. That gives $51 against a price of $45.49 — about +12%, with a 12-month target of $50. Fair value crosses the current price at roughly $3.20 of 2027 earnings on a 14 multiple. We accumulate below $40, near the March low, where the Bear case alone covers the price.
Multiples
P/E trailing
~13x
P/E on FY2026E
~13x
P/E on our 2027 Base
~14x
Sector median P/E
~15x
What could go wrong
4 risks, in order
01The price cut is not offset by volume
The central risk, and the one the whole rating turns on. Watch first-quarter 2027 US sales against volumes: if sales fall more than the price cut implies, volume is not responding at all and the Bear case becomes the base case.
02Further share loss to Eli Lilly
Lilly is larger and guiding up while Novo guides down. Losing leadership in new patient starts for two consecutive quarters would be a thesis-breaker: share, once lost in this category, has not historically come back.
03Patents expire abroad from 2026
Semaglutide patents begin expiring in international markets from 2026, with Chinese biosimilars ready. High probability, medium severity — it shows up in the international sales mix rather than in one quarter.
04Another pipeline failure after ZEUS
Ziltivekimab missed its primary endpoint and the quarter carried DKK 6.3bn of impairments, DKK 4.0bn of it on monlunabant. One is a setback; two would be a research problem.
In conclusion
The free summary ends here
Where we stand
HOLD
Fair value $51, 12-month target $50, low conviction. Novo Nordisk is a high-quality business trading at a mature-pharmaceutical multiple after a 70% de-rating, with the strongest product launch its industry has seen currently in progress. It is also five months away from cutting its own American prices by up to half. Those two facts very nearly cancel, and 12% is not enough to underwrite the difference. Accumulate below $40.