Milano––:––apertachiusa. Orario regolare di contrattazione, con le festività di ciascuna borsa: quelle di Borsa Italiana per Milano, quelle del NYSE per New York.
New York––:––apertachiusa. Orario regolare di contrattazione, con le festività di ciascuna borsa: quelle di Borsa Italiana per Milano, quelle del NYSE per New York.
Semiconductors — Wafer-Scale AI Compute & Inference Cloud
The largest chip in the world, and what the market is paying for it
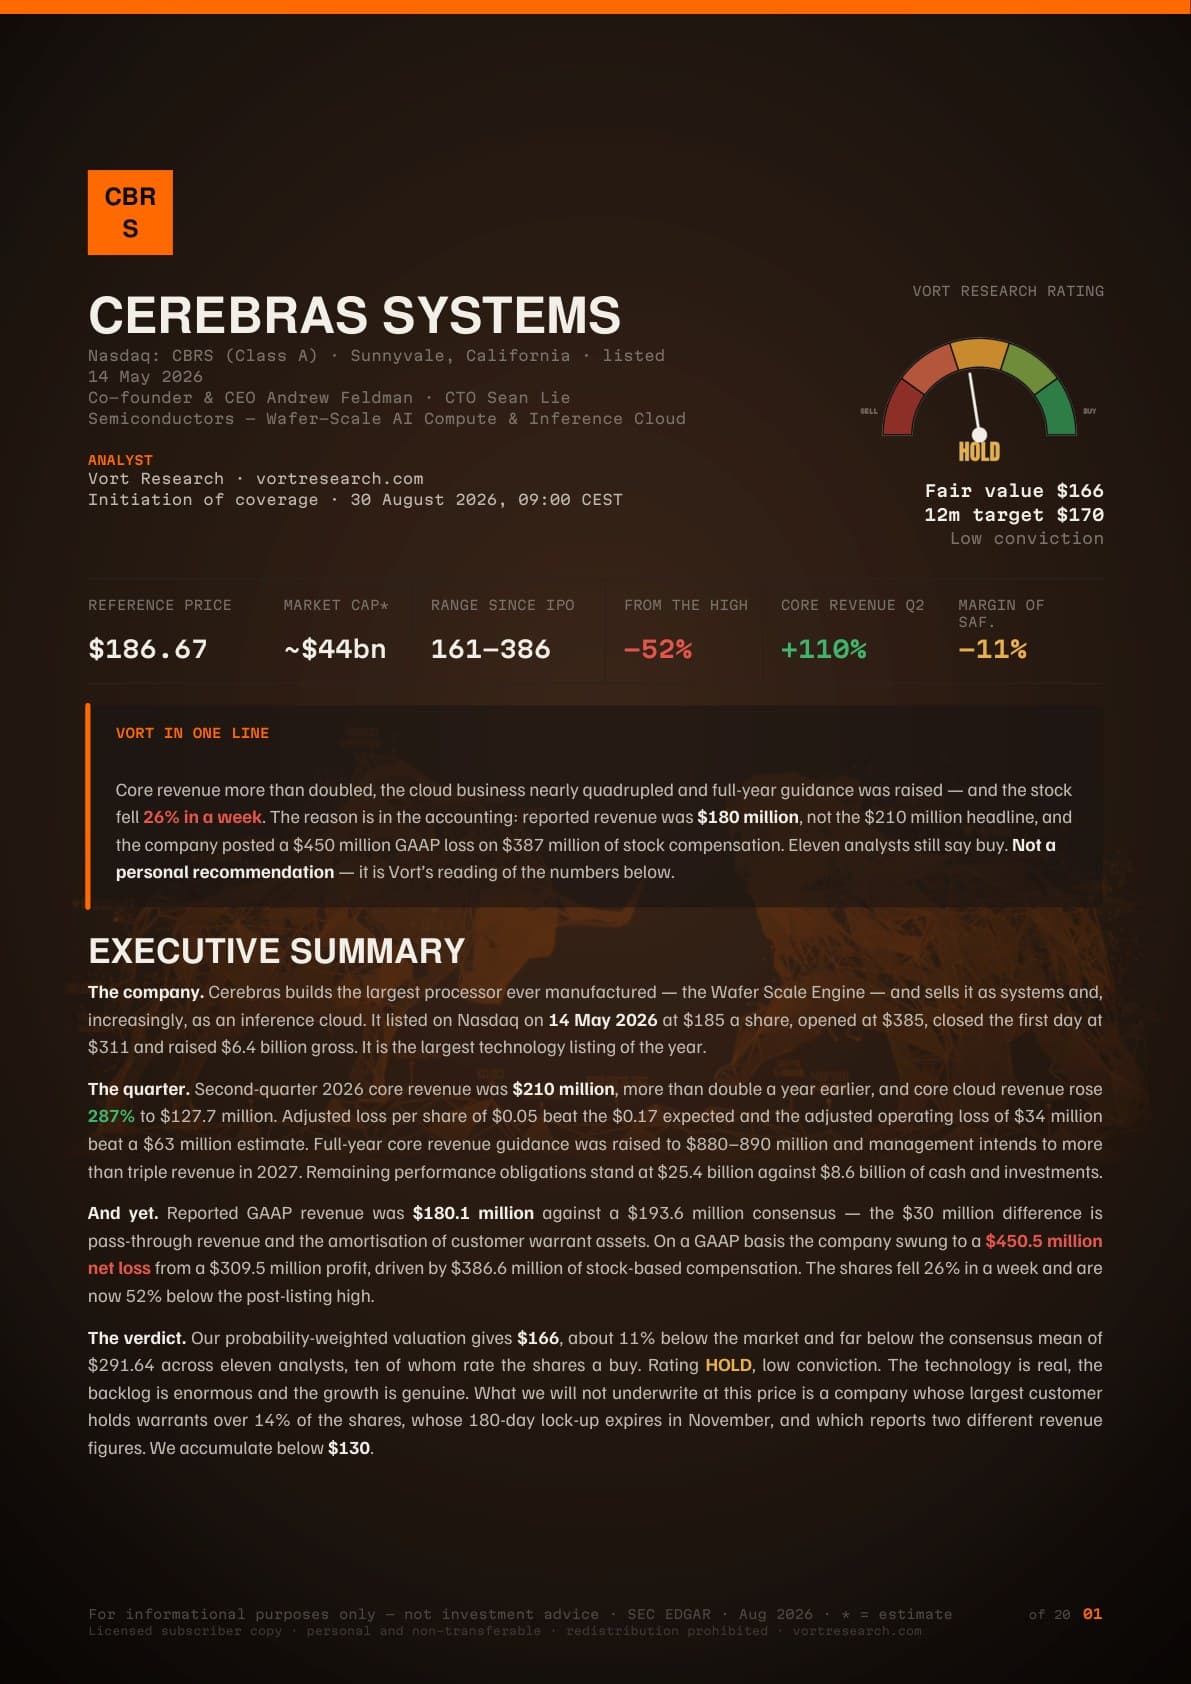
Core revenue more than doubled, the cloud business nearly quadrupled and full-year guidance was raised — and the stock fell 26% in a week. The reason is in the accounting: reported revenue was $180 million, not the $210 million headline, and the company posted a $450 million GAAP loss on $387 million of stock compensation.
▲ Variazione sulla chiusura precedente: +0,49% (+0,69 USD)
Potenziale al fair value
+17%
dall’ultima chiusura
Obiettivo raggiunto. Il prezzo di mercato è sceso fino al fair value indicato nel report del 30 agosto 2026. Il giudizio resta quello del documento: un obiettivo centrato non è una nuova raccomandazione.
Il mercato USA è chiuso: il prezzo è quello di chiusura del 15 ottobre 2026. In seduta la quotazione è differita fino a 15 minuti. Il fair value è quello del report del 30 agosto 2026 e non si aggiorna con il mercato. Vort Research fornisce contenuti informativi ed educativi. Non è consulenza finanziaria personalizzata né sollecitazione all’investimento.
Il report completo è riservato agli abbonati Vort+.
Giudizio, fair value e ragionamento di questa pagina sono pubblici. Il PDF e le slide si scaricano con Vort+; se ce l’hai già, accedi.
Wafer-scale sidesteps high-bandwidth memory, advanced packaging and leading-edge fabrication — the three constraints throttling GPU supply. In a market where compute demand exceeds supply, a manufacturer not queuing behind the same bottleneck has a structural advantage.
Two revenue figures, one very different from the other.
Core revenue of $210 million strips out the amortisation of warrants issued to OpenAI. GAAP revenue was $180.1 million. The company is paying its largest customer in equity and excluding the cost from its growth metric.
The price already pays for the tripling.
At $186.67 the enterprise value is roughly 40× 2026 core revenue. For the stock to work from here, 2027 revenue must triple as guided — and management has promised and not yet delivered.
core revenue growth, Q2
+110%
cloud revenue growth
+287%
GAAP net loss, Q2
−$450m
remaining performance obligations
$25.4bn
I conti in sintesi
Second quarter 2026, reported 12 August
Core revenue Q2
$210m
↗ in aumento: +110%
GAAP revenue Q2
$180.1m
Core cloud revenue Q2
$127.7m
↗ in aumento: +287%
FY26 core revenue guidance
$880–890m
↗ in aumento: raised
GAAP net loss Q2
−$450.5m
Stock-based compensation Q2
$386.6m
Cash & investments
$8.6bn
Remaining perf. obligations
$25.4bn
L’analisi
Sintesi gratuita
Two revenue figures
Cerebras reports core revenue of $210m and GAAP revenue of $180.1m. The $30m gap is mostly the amortisation of warrants over ~33.4 million shares issued to OpenAI. The company is paying its largest customer in equity and excluding the cost from its growth metric.
From a $34m loss to a $450m loss
An adjusted operating loss of $34m is a respectable result for a company scaling infrastructure. A GAAP net loss of $450.5m is a different proposition. The bridge is almost entirely $386.6m of stock-based compensation, most triggered by the listing itself.
The backlog and the customer
$25.4bn of remaining performance obligations against $885m of 2026 revenue — roughly 29×. The overwhelming majority belongs to OpenAI, whose compute commitment is reported above $20bn. Extreme customer concentration is the strongest evidence and the largest risk at the same time.
The company is paying its largest customer in equity and excluding the cost from its growth metric.
Vort Research — Cerebras initiation, 30 August 2026
Cosa fa, e come guadagna
Il mestiere
Cerebras builds the largest processor ever manufactured — the Wafer Scale Engine — and sells it as systems and, increasingly, as an inference cloud. It listed on Nasdaq on 14 May 2026 at $185 a share, raised $6.4 billion gross and is the largest technology listing of the year.
Da dove vengono i ricavi
Inference cloud (recurring compute)~61% of core revenue
CS systems (on-premises wafer-scale)lumpy
Multi-year compute contracts$25.4bn RPO
Il modello
Wafer-scale architecture avoids the HBM, advanced packaging and leading-edge fab bottlenecks that constrain GPU supply. The commercial pitch is speed: fast tokens at a premium price.
Il giudizio Vort in quattro voci
È una sintesi qualitativa e non è una raccomandazione.
Technology
✓Differentiated
The only wafer-scale processor at commercial scale; avoids the GPU supply bottleneck.
Accounts
×Pre-profit
No earnings on any basis. $387m of stock comp turned an adjusted $34m loss into a $450m GAAP loss.
Valuation
×Expensive
~40× 2026 core revenue. The price pays in full for a 2027 tripling not yet delivered.
Concentration
±Extreme
One counterparty dominates the $25.4bn backlog; a November lock-up expiry adds supply risk.
Con chi compete
Società
Dove compete
Cerebras SystemsQuesto titolo
Wafer-scale AI compute and inference cloud
Nvidia
The incumbent — AI training and inference, with the software ecosystem
AMD
Inference accelerators; also a Cerebras partner on Helios
Google TPU
Vertically integrated internal and cloud inference
Groq, SambaNova
Same fast-inference architectural argument, smaller scale
Cerebras is not building a cheaper GPU; it is arguing that keeping an entire model on one piece of silicon removes the communication overhead that dominates inference latency.
Come lo valutiamo
Il numero e il ragionamento
Fair value Vort
$166
A probability-weighted valuation across scenarios running from $88 to $279, against a price of $186.67 — about −11%. The 12-month target is $170. This is the widest gap to consensus in the Vort coverage universe: 10 of 11 analysts rate it buy with a mean target of $291.64. We accumulate below $130.
Multipli
EV / FY26E core revenue
~40×
EV / FY27E revenue
~13×
P/E
no earnings
Cash & investments
$8.6bn
Cosa può andare storto
4 rischi, in ordine
012027 revenue does not triple
The stock is priced for a tripling that management has promised and not delivered. If revenue doubles instead, the Bear case at $88 applies.
02Customer concentration event
OpenAI dominates the $25.4bn backlog. Any change in that relationship — funding, priorities, in-house alternatives — would be existential for the revenue line.
03Lock-up expiry in November
A standard 180-day restriction from a 14 May listing releases pre-IPO holders into a market where the shares already trade near the offer price.
04Gross margin stays near 36%
Renting back systems from a customer costs ten to fifteen points of cloud margin. The arrangement is temporary but the guided 36–38% is well below software multiples.
In conclusione
La sintesi gratuita finisce qui
Dove ci posizioniamo
HOLD
Fair value $166, 12-month target $170, low conviction. The technology is differentiated and the cloud transition is working — but $180 million of GAAP revenue, a $450 million loss, extreme customer concentration and a November lock-up do not support the price the market is asking. We accumulate below $130.