Milano––:––apertachiusa. Orario regolare di contrattazione, con le festività di ciascuna borsa: quelle di Borsa Italiana per Milano, quelle del NYSE per New York.
New York––:––apertachiusa. Orario regolare di contrattazione, con le festività di ciascuna borsa: quelle di Borsa Italiana per Milano, quelle del NYSE per New York.
The market is pricing a permanent halving of earnings
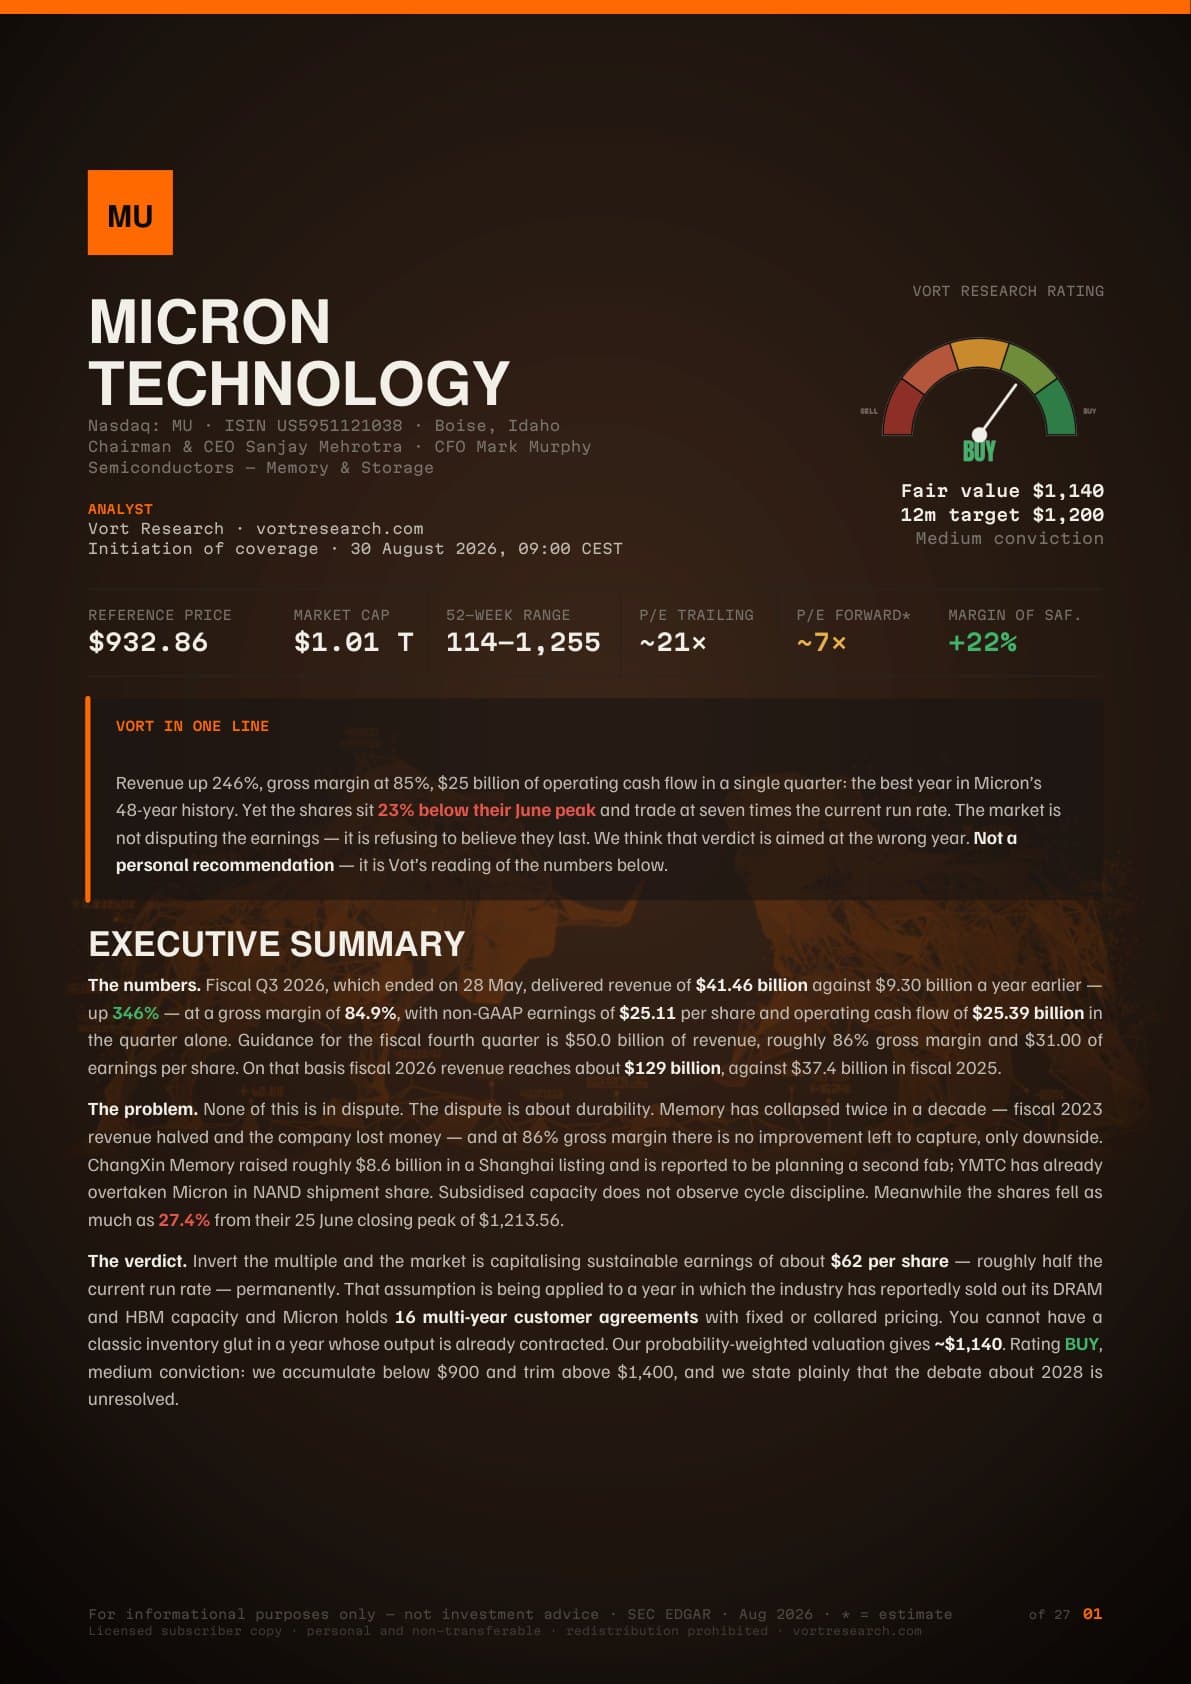
Revenue up 246%, gross margin at 85%, $25bn of operating cash flow in a single quarter — the best year in Micron's 48-year history. Yet the shares sit 23% below their June peak and trade at seven times the current run rate. The market is not disputing the earnings; it is refusing to believe they last.
▲ Variazione sulla chiusura precedente: +1,87% (+17,11 USD)
Potenziale al fair value
+22%
dall’ultima chiusura
932,86 USD al report1140 USD fair value
Il mercato USA è chiuso: il prezzo è quello di chiusura del 15 ottobre 2026. In seduta la quotazione è differita fino a 15 minuti. Il fair value è quello del report del 30 agosto 2026 e non si aggiorna con il mercato. Vort Research fornisce contenuti informativi ed educativi. Non è consulenza finanziaria personalizzata né sollecitazione all’investimento.
Il report completo è riservato agli abbonati Vort+.
Giudizio, fair value e ragionamento di questa pagina sono pubblici. Il PDF e le slide si scaricano con Vort+; se ce l’hai già, accedi.
Fiscal Q3 delivered $41.46bn of revenue against $9.30bn a year earlier, at an 84.9% gross margin, and $25.39bn of operating cash flow in the quarter alone. This is not a receivable and not a revaluation: it is money that arrived.
The output is already sold.
The industry has reportedly sold out DRAM and HBM capacity for 2027, and Micron holds 16 multi-year customer agreements with fixed or collared pricing. A classic inventory glut is hard to have in a year whose production is contracted in advance.
The market is pricing the wrong year.
Invert the multiple and the shares capitalise sustainable earnings of about $62 — roughly half the current run rate — permanently. That is a verdict on 2028, applied to 2026.
revenue growth FY26E
+246%
gross margin, Q3
84.9%
operating cash flow, one quarter
$25.4bn
multi-year agreements
16
I conti in sintesi
Fiscal Q3 2026, ended 28 May
Revenue FY26E
$129.0bn
↗ in aumento: +245%
Revenue FY25
$37.4bn
↗ in aumento: +49%
Gross margin FY26E
~75%
↗ in aumento: from ~39%
Operating cash flow FY26E
~$70bn
EPS non-GAAP FY26E
~$73
Q4 EPS, guidance
$31.00
Cash & investments
$30.2bn
Dividend per share
$0.60
unchanged
L’analisi
Sintesi gratuita
Why the arithmetic broke
An AI training server uses roughly eight to ten times the DRAM of a conventional server and more than three times the NAND. Worse for buyers, high-bandwidth memory consumes far more wafer area per usable bit than ordinary memory, so every wafer redirected to HBM removes several wafers of conventional supply from the market. The shortage is not a forecasting error. It is arithmetic.
Three manufacturers, and no fourth
Micron is one of only three companies in the world producing DRAM at scale, alongside Samsung and SK Hynix. New capacity is measured in years and in tens of billions of dollars, which is why a demand shock of this size cannot be answered inside a cycle.
The operating leverage cuts both ways
Against a fixed cost base, operating expenses are roughly 3% of revenue while gross margin has gone from about 39% to about 86%. That is the whole bull case — and the whole bear case. At 86% there is no improvement left to capture, only downside.
You cannot have a classic inventory glut in a year whose output is already contracted.
Vort Research — Micron initiation, 30 August 2026
Cosa fa, e come guadagna
Il mestiere
Micron designs and manufactures memory. DRAM holds the data a processor is working on; NAND flash keeps it when the power is off. Inside DRAM sits the product that has transformed the company: high-bandwidth memory, in which DRAM dies are stacked vertically and bonded directly beside an AI accelerator.
Da dove vengono i ricavi
DRAM, including HBM~75%
NAND and storage~22%
Other~3%
Il modello
Capital-intensive manufacturing inside a three-player structure. The moat is not a patent but qualification: an accelerator maker that has certified a memory supplier does not change it lightly, and every new HBM generation extends that lock.
Il giudizio Vort in quattro voci
È una sintesi qualitativa e non è una raccomandazione.
Business
✓Strong
One of three DRAM makers at scale, in the year its product became the constraint on AI.
Accounts
✓Very strong
$25.4bn of operating cash flow in a single quarter and $30.2bn of cash and investments.
Valuation
±Attractive on this year
About 7.5x the current run rate. The multiple is low because nobody believes the year.
Cyclicality
×The real risk
Memory has collapsed twice in a decade. At an 86% margin there is nothing left to gain.
Con chi compete
Società
Dove compete
Micron TechnologyQuesto titolo
DRAM, HBM and NAND — the only US maker at scale
SK Hynix
The HBM leader by share, and the reference on qualification
Samsung Electronics
The largest memory maker, catching up on HBM
ChangXin Memory (CXMT)
Chinese DRAM, state-funded, raised ~$8.6bn in Shanghai
YMTC
Chinese NAND, already ahead of Micron on shipment share
The structure of this industry is the investment case. Three companies decide global DRAM supply, and the fourth entrant is being built with state money that does not observe cycle discipline. That is the opportunity and the threat in one sentence.
Come lo valutiamo
Il numero e il ragionamento
Fair value Vort
$1,140
A probability-weighted valuation across scenarios running from $420 to $1,820, against a price of $932.86 — about +22%. The 12-month target is $1,200. The single assumption that matters is normalised earnings: the market capitalises about $62 per share, we work from a higher and partly contracted base. We accumulate below $900 and trim above $1,400, and we say plainly that the debate about 2028 is unresolved.
Multipli
P/E trailing
~21x
P/E on Q4 run rate
~7.5x
P/E on normalised EPS
~12x
EV / Revenue FY26E
~8x
Cosa può andare storto
4 rischi, in ordine
01The margin has no upside and enormous downside
At about 86% gross margin there is no improvement left to capture. Every path from here is a lower margin, and the only question is when.
02Chinese capacity built with state money
ChangXin raised roughly $8.6bn in a Shanghai listing and is reported to be planning a second fab; YMTC has already overtaken Micron in NAND shipment share. Subsidised capacity does not observe cycle discipline.
03Every prior peak ended in collapse
Twice in a decade. Fiscal 2023 revenue halved and the company lost money. Nothing here says the cycle has been abolished — only that it has not turned yet.
04The contracts have to be renewed
The 16 agreements are why 2026 and 2027 are defensible. They are also the thing to watch: if hyperscaler AI capex softens before renewal, the pricing floor goes with it.
In conclusione
La sintesi gratuita finisce qui
Dove ci posizioniamo
BUY
Fair value $1,140, 12-month target $1,200, medium conviction. The business is not in question: revenue is up 346% year on year, the margin is at a level most software companies never reach, and the cash has already arrived. What is in question is how long it lasts — and on that we accept the uncertainty rather than dress it up. Accumulate below $900, trim above $1,400.