Milano––:––apertachiusa. Orario regolare di contrattazione, con le festività di ciascuna borsa: quelle di Borsa Italiana per Milano, quelle del NYSE per New York.
New York––:––apertachiusa. Orario regolare di contrattazione, con le festività di ciascuna borsa: quelle di Borsa Italiana per Milano, quelle del NYSE per New York.
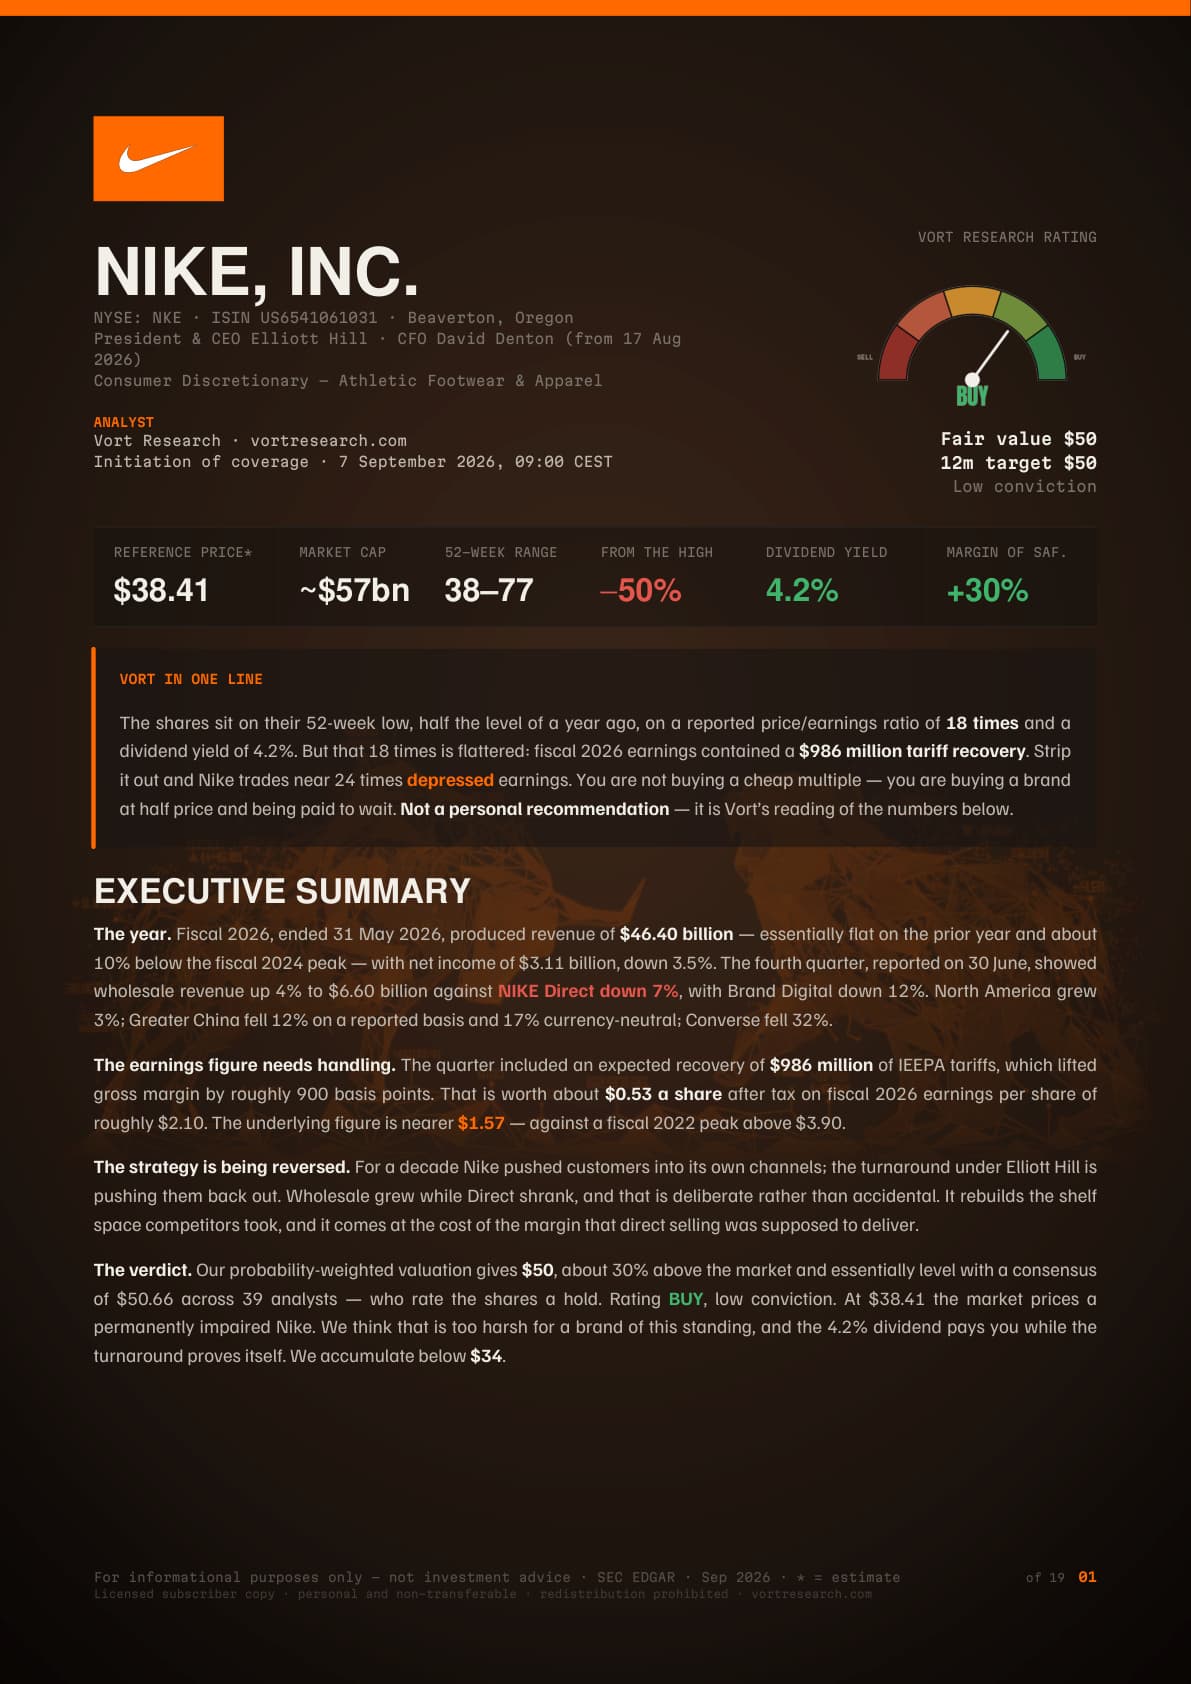
The shares sit on their 52-week low, half the level of a year ago, on a reported price/earnings ratio of 18 times and a dividend yield of 4.2%. But that 18 times is flattered: fiscal 2026 earnings contained a $986 million tariff recovery. Strip it out and Nike trades near 24 times depressed earnings. You are not buying a cheap multiple — you are buying a brand at half price and being paid to wait.
Il link di download si crea quando premi e vale dieci minuti.
Giudizio
Buy
Fair value
50 USD
Ultima chiusura
37,14 USD
▲ Variazione sulla chiusura precedente: +5,21% (+1,84 USD)
Potenziale al fair value
+35%
dall’ultima chiusura
38,41 USD al report50 USD fair value
Il mercato USA è chiuso: il prezzo è quello di chiusura del 15 ottobre 2026. In seduta la quotazione è differita fino a 15 minuti. Il fair value è quello del report del 7 settembre 2026 e non si aggiorna con il mercato. Vort Research fornisce contenuti informativi ed educativi. Non è consulenza finanziaria personalizzata né sollecitazione all’investimento.
Fiscal 2026 earnings contain an expected recovery of $986 million of tariffs — worth about $0.53 a share after tax. Reported earnings per share of roughly $2.10 are nearer $1.57 underneath, so the 18 times on the screen is closer to 24 times. You are not buying a cheap multiple.
You are buying a brand at half price, and being paid to wait.
The shares have fallen from $76.97 to $38.41 and sit about 1% above their 52-week low. The dividend yields 4.2% and is covered by earnings that are themselves depressed. Few turnarounds pay this well for patience.
The decline has stopped. The recovery has not started.
Revenue was $46.40 billion, up 0.2% after a 10% fall — two years after the peak the top line has stabilised without recovering. Both halves of that sentence are true, and the market is pricing only the second.
from the 52-week high
−50%
dividend yield, covered
4.2%
one-off tariff recovery in Q4
$986m
North America, the one market growing
+3%
I conti in sintesi
Fiscal year 2026, ended 31 May, reported 30 June
FY2026 revenue
$46.40bn
↗ in aumento: +0.2%
FY2026 net income
$3.11bn
↘ in calo: −3.5%
EPS reported
~$2.10
EPS ex-tariff recovery
~$1.57
↘ in calo: −25%
Q4 wholesale
+4%
↗ in aumento: rebuilding
Q4 NIKE Direct
−7%
↘ in calo: de-emphasised
Q4 Greater China
−12%
↘ in calo: −17% cn
Q4 Converse
−32%
↘ in calo: all territories
L’analisi
Sintesi gratuita
What the reported earnings contained
The fourth quarter included an expected recovery of $986 million of tariffs levied under emergency powers and later reversed, lifting the quarter's gross margin by roughly 900 basis points. It is real cash and it is, by definition, non-recurring. Strip it out and the honest multiple is 24 times — on earnings that are themselves depressed against a fiscal 2022 peak above $3.90.
A decade of strategy, reversed on purpose
From about 2017 Nike pulled demand into its own stores and app. It worked on margin and failed on distribution: the shelf space it vacated was filled by someone else. The quarter shows the reversal — wholesale +4%, Direct −7%, Brand Digital −12%. The risk is not that wholesale fails to rebuild; it is that Direct falls faster than wholesale recovers.
Three geographies, three different problems
North America grew 3% and was the sole growth driver — the evidence the plan works where it has been applied first. Greater China fell 12%, and 17% currency-neutral, against domestic brands that have taken the category. No part of our Base case assumes China returns to growth.
The decline has stopped. The recovery has not started. Both statements are true, and the market is currently pricing only the second.
Vort Research — Nike initiation, 7 September 2026
Cosa fa, e come guadagna
Il mestiere
Nike designs and sells athletic footwear and apparel. It owns the Nike, Jordan and Converse brands, sells through wholesale partners and its own stores and digital channels, and operates across North America, EMEA, Greater China and Asia Pacific. It has been the dominant brand in its category for four decades.
Da dove vengono i ricavi
Wholesale — through retail partners+4% in Q4
NIKE Direct — own stores and digital−7% in Q4
Converse — heritage casual−32% in Q4
Il modello
The two channels differ sharply. Direct carries the full retail margin plus the cost of stores and customer acquisition; wholesale gives margin away to the retailer but occupies shelf space that would otherwise hold a competitor.
Il giudizio Vort in quattro voci
È una sintesi qualitativa e non è una raccomandazione.
Brand
✓First rank
Four decades of category leadership. The cultural position was never lost — the shelf space was.
Dividend
✓4.2%, covered
Paid while the turnaround proves itself, and covered by earnings that are already depressed.
Turnaround
±Early
North America grew 3% and wholesale rebuilt. Two years of effort have still produced flat revenue.
China
×Still falling
−12%, and −17% currency-neutral, against domestic brands. Our Base case assumes it never recovers.
Con chi compete
Società
Dove compete
NIKEQuesto titolo
Three brands, two channels, four geographies
On Holding
Running, premium — took the share Nike vacated at speciality retail
Deckers (Hoka)
The same playbook, a different silhouette
Adidas
Recovered strongly from a crisis of its own
Anta, Li-Ning
The reason Greater China is not coming back quickly
New entrants scores unusually high for a category this old, and that is the heart of the problem: On and Hoka went from nothing to material share inside a decade, which proved that a distinctive product plus running-store distribution can breach what looked like an impregnable brand.
Come lo valutiamo
Il numero e il ragionamento
Fair value Vort
$50
A probability-weighted valuation on fiscal 2029 earnings — three years out, because a consumer turnaround is not resolved inside a single year — across scenarios from $29 to $86, against a price of $38.41: about +30%. Our $50 sits almost exactly on the consensus of $50.66 across 39 analysts, who rate the shares a hold. The rating differs because the arithmetic does: 30% of upside clears our buy threshold. We accumulate below $34.
Multipli
P/E reported FY2026
~18.3×
P/E ex-tariff recovery
~24×
P/E on FY2029E Base
~14×
Dividend yield
~4.2%
Cosa può andare storto
4 rischi, in ordine
01The brand impairment proves permanent
Consumer brands do lose their position for good — it has happened to companies that looked as secure as this one. Our Bear case carries a 40% weight for exactly that reason, and it values the shares at $29.
02Greater China keeps declining
High probability, high severity. Domestic brands have taken the category and the consumer environment is weak. What was the growth engine is now a drag.
03Direct falls faster than wholesale rebuilds
Total revenue stays flat while the mix shifts toward the lower-margin channel. That is precisely what fiscal 2026 looked like.
04A dividend cut
Low probability, high severity. At 4.2% the yield is a material part of the case; a cut would remove the compensation for waiting.
In conclusione
La sintesi gratuita finisce qui
Dove ci posizioniamo
BUY
Fair value $50, 12-month target $50, low conviction. At $38.41 the market prices a permanently impaired Nike — a brand that never again earns what it earned four years ago. North America growing, wholesale rebuilding and a covered 4.2% dividend argue that is too harsh. The counterweight is honest: two years of turnaround have produced flat revenue, China is still falling, and the reported multiple is flattered by a one-off. We accumulate below $34 — and first-quarter results land within three weeks of publication.