Milano––:––apertachiusa. Orario regolare di contrattazione, con le festività di ciascuna borsa: quelle di Borsa Italiana per Milano, quelle del NYSE per New York.
New York––:––apertachiusa. Orario regolare di contrattazione, con le festività di ciascuna borsa: quelle di Borsa Italiana per Milano, quelle del NYSE per New York.
Semiconductors — Accelerated Computing & AI Infrastructure
The largest company in the world, still accelerating
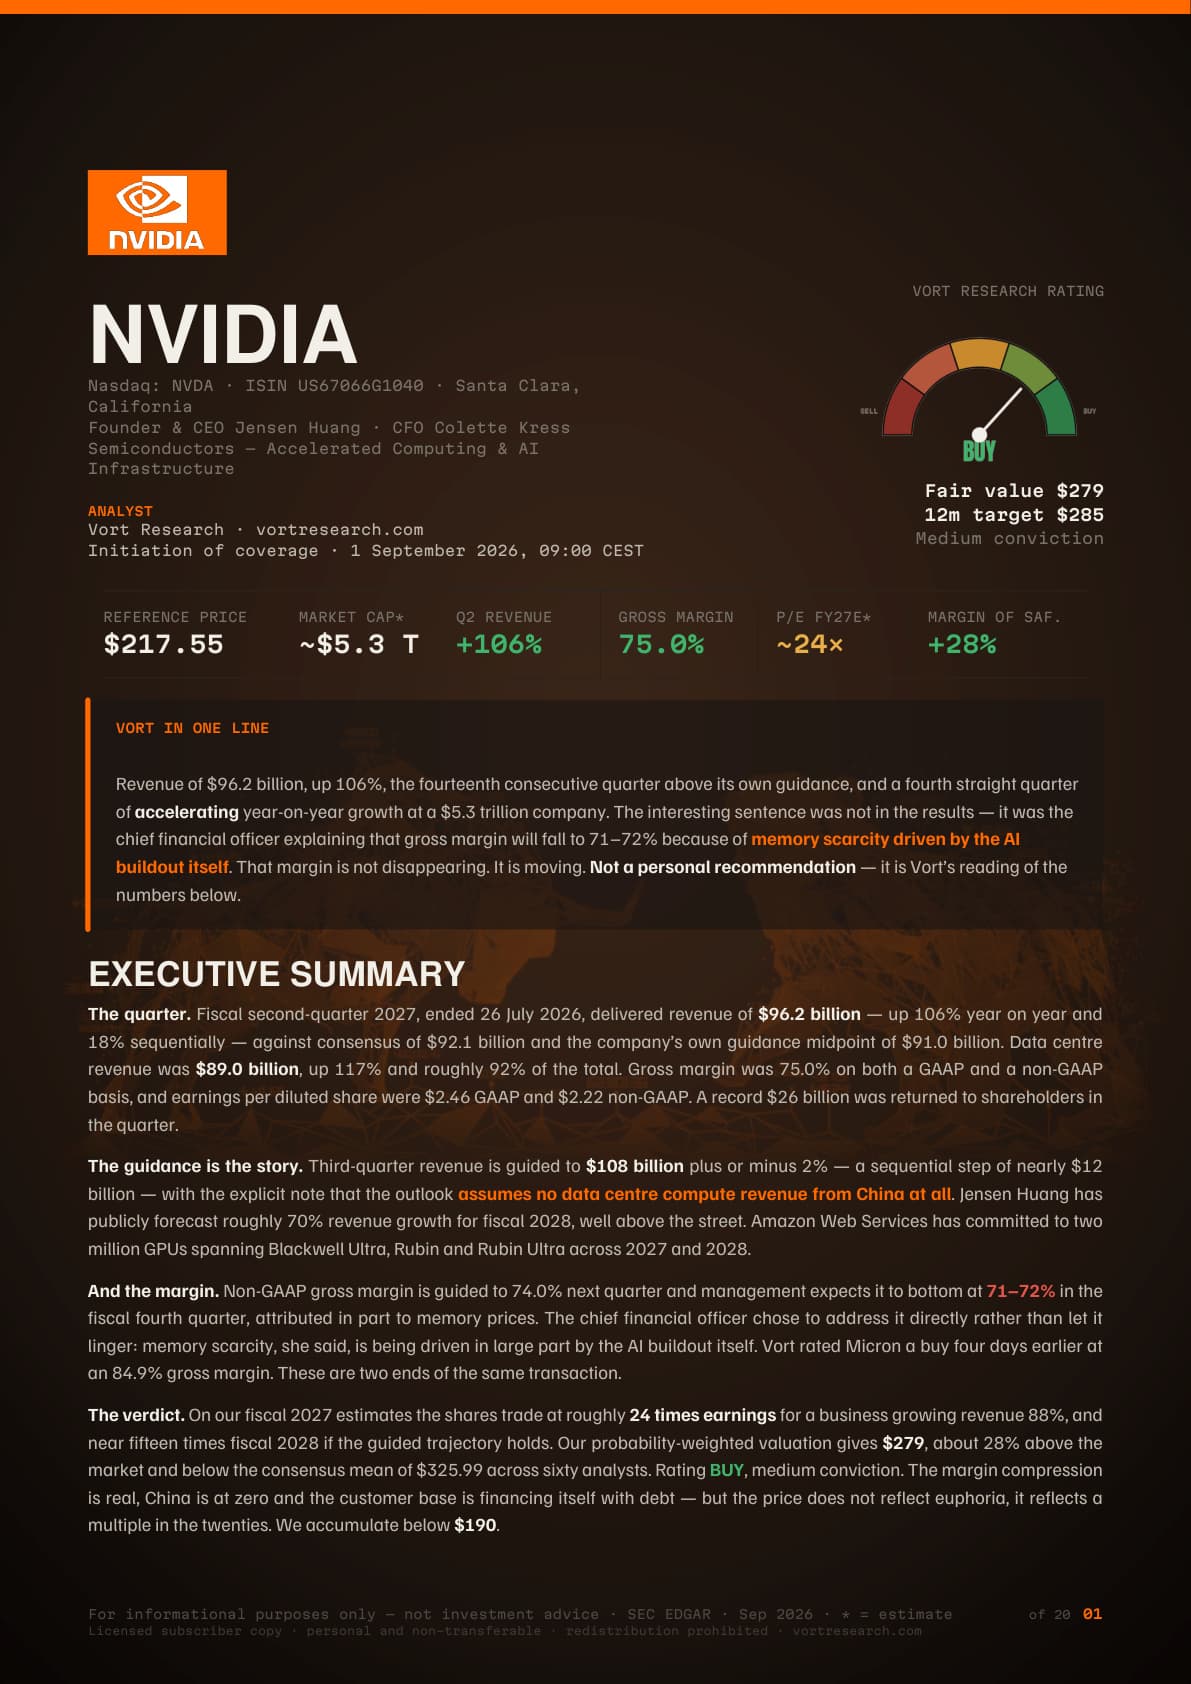
Revenue of $96.2 billion, up 106%, the fourteenth consecutive quarter above its own guidance, and a fourth straight quarter of accelerating growth at a $5.3 trillion company. The interesting sentence was not in the results — it was the chief financial officer explaining that gross margin will fall to 71–72% because of memory scarcity driven by the AI buildout itself. That margin is not disappearing. It is moving.
Il link di download si crea quando premi e vale dieci minuti.
Giudizio
Buy
Fair value
279 USD
Ultima chiusura
217,23 USD
▼ Variazione sulla chiusura precedente: -1,84% (-4,07 USD)
Potenziale al fair value
+28%
dall’ultima chiusura
217,55 USD al report279 USD fair value
Il mercato USA è chiuso: il prezzo è quello di chiusura del 15 ottobre 2026. In seduta la quotazione è differita fino a 15 minuti. Il fair value è quello del report del 1 settembre 2026 e non si aggiorna con il mercato. Vort Research fornisce contenuti informativi ed educativi. Non è consulenza finanziaria personalizzata né sollecitazione all’investimento.
Twenty-four times earnings is not a euphoric multiple.
On our fiscal 2027 estimates the shares trade at roughly 24× earnings for a business growing revenue 88% — a growth-adjusted ratio below one — and near fifteen times fiscal 2028 if the guided trajectory holds. The prevailing narrative is that NVIDIA is expensive. The arithmetic says otherwise.
The margin is not disappearing. It is moving.
Gross margin is guided from 75.0% down to a 71–72% trough, attributed in part to memory prices — scarcity driven by the AI buildout itself. Vort rated Micron a buy four days earlier at an 84.9% gross margin. These are two ends of the same transaction.
China is at zero, so it is upside rather than risk.
The $108 billion third-quarter guide carries an explicit footnote: no data centre compute revenue from China at all. Every estimate here makes the same assumption, which means any policy change is an option nobody is paying for.
revenue growth, Q2 FY2027
+106%
data centre revenue, ~92% of total
$89.0bn
consecutive quarters above guidance
14
returned to shareholders in the quarter
$26bn
I conti in sintesi
Second quarter fiscal 2027, reported 26 August
Revenue Q2 FY27
$96.2bn
↗ in aumento: +106%
Data centre revenue Q2
$89.0bn
↗ in aumento: +117%
Gross margin Q2
75.0%
EPS non-GAAP Q2
$2.22
↗ in aumento: vs $2.09
EPS GAAP Q2
$2.46
Q3 revenue guidance
$108bn ±2%
↗ in aumento: +89%
Q3 gross margin guidance
74.0%
↘ in calo: −100bps
Q4 gross margin trough
71–72%
↘ in calo: guided
L’analisi
Sintesi gratuita
The guidance is the story
A guide of $108 billion implies a sequential increase of nearly $12 billion — more than the entire quarterly revenue of most semiconductor companies — and it excludes China entirely. Fourteen consecutive quarters above guidance is a pattern the market has learned to price, which is why beating by 5.7% produced an 8.7% share price move rather than a 20% one.
Where the margin is going
Three and a half points of gross margin on a business running at a $430 billion annual revenue rate is a very large number. What makes it worth a section rather than a footnote is the explanation: the company's own demand is bidding up the price of its own inputs. Management named the level and the quarter in advance rather than letting it emerge.
Who is buying, and how they are paying
Amazon Web Services has committed to two million GPUs spanning Blackwell Ultra, Rubin and Rubin Ultra — while embedding NVIDIA's interconnect inside its own Trainium racks. But analysts at BlackRock flagged roughly $100 billion of hyperscaler debt issuance. NVIDIA's revenue is its customers' capital expenditure, and an increasing share of it is financed rather than funded from cash flow.
That margin is not disappearing. It is moving.
Vort Research — NVIDIA initiation, 1 September 2026
Cosa fa, e come guadagna
Il mestiere
NVIDIA sells accelerated computing: graphics processors, the networking that joins them into clusters, the CPUs that feed them and the software layer that makes the whole assembly programmable. Roughly 92% of revenue now comes from the data centre segment, which means that for practical purposes this is a company selling AI infrastructure with a gaming business attached.
Da dove vengono i ricavi
Data centre (GPUs, networking, CPUs, systems)~92% of revenue
Gaming, professional visualisation, automotive~8% of revenue
NVLink Fusion licensed to third partiesexpanding
Il modello
The moat is the software ecosystem, not the transistor count. NVLink Fusion licenses the interconnect to companies building custom accelerators — NVIDIA earning from the chips designed to displace it.
Il giudizio Vort in quattro voci
È una sintesi qualitativa e non è una raccomandazione.
Growth
✓Accelerating
Fourth consecutive quarter of accelerating year-on-year growth, at $5.3 trillion of value.
Valuation
✓Reasonable
~24× fiscal 2027 earnings on 88% revenue growth; near 15× on the guided 2028.
Margin
±Compressing
Guided from 75% to a 71–72% trough on memory costs. Pre-announced, but real.
Concentration
×High
Nine tenths of revenue in one segment; a handful of customers, several financing with debt.
Con chi compete
Società
Dove compete
NVIDIAQuesto titolo
The incumbent — accelerated computing and the software ecosystem
AMD
The only credible merchant alternative
Google TPU
Vertically integrated, internal and cloud — not sold merchant
Broadcom
Custom XPU design; NVHBM positions NVIDIA against it
Cerebras, Groq
Fast inference on a different architecture, small scale so far
Supplier power is now the strongest adverse force and this is a change: memory manufacturers and advanced packaging capacity are the constraint, and the margin guidance is the visible proof.
Come lo valutiamo
Il numero e il ragionamento
Fair value Vort
$279
A probability-weighted valuation across scenarios running from $189 to $398, against a price of $217.55 — about +28%. The 12-month target is $285. Our number sits 14% below the consensus mean of $325.99 across sixty analysts, almost entirely because we carry the margin trough through fiscal 2028 rather than assuming a rapid recovery. We accumulate below $190.
Multipli
P/E trailing FY26E
~44×
P/E on FY2027E
~24×
P/E on FY2028E
~15×
Consensus target
$325.99
Cosa può andare storto
4 rischi, in ordine
01Hyperscaler capital expenditure pauses
NVIDIA's revenue is its customers' spending. A named hyperscaler publicly reducing AI capex would reset the sector multiple with it. Medium probability, very high severity.
02Customers' debt financing tightens
Roughly $100 billion of hyperscaler debt issuance follows this print. A tightening in credit markets would reach this income statement faster than any competitive development.
03The margin trough goes below 70% and stays there
The guided 71–72% is a floor management named in advance. Below 70% with no stated path back, the memory cost pressure has become structural rather than cyclical.
04Size limits further re-rating
At $5.3 trillion, a doubling requires adding the value of several mega-caps. This is certain rather than probable — the question is only how much it weighs.
In conclusione
La sintesi gratuita finisce qui
Dove ci posizioniamo
BUY
Fair value $279, 12-month target $285, medium conviction. The prevailing view is that NVIDIA is expensive. On our fiscal 2027 estimates it trades near twenty-four times earnings while growing revenue 88%, guides to $108 billion with China set to zero, and has beaten its own outlook fourteen quarters running. The margin compression is real and we carry it through the model rather than assuming it away. We accumulate below $190 and hold this alongside Micron, because the margin one is losing is largely the margin the other is collecting.