Milano––:––apertachiusa. Orario regolare di contrattazione, con le festività di ciascuna borsa: quelle di Borsa Italiana per Milano, quelle del NYSE per New York.
New York––:––apertachiusa. Orario regolare di contrattazione, con le festività di ciascuna borsa: quelle di Borsa Italiana per Milano, quelle del NYSE per New York.
Consumer Discretionary — Electric Vehicles, Energy & Autonomy
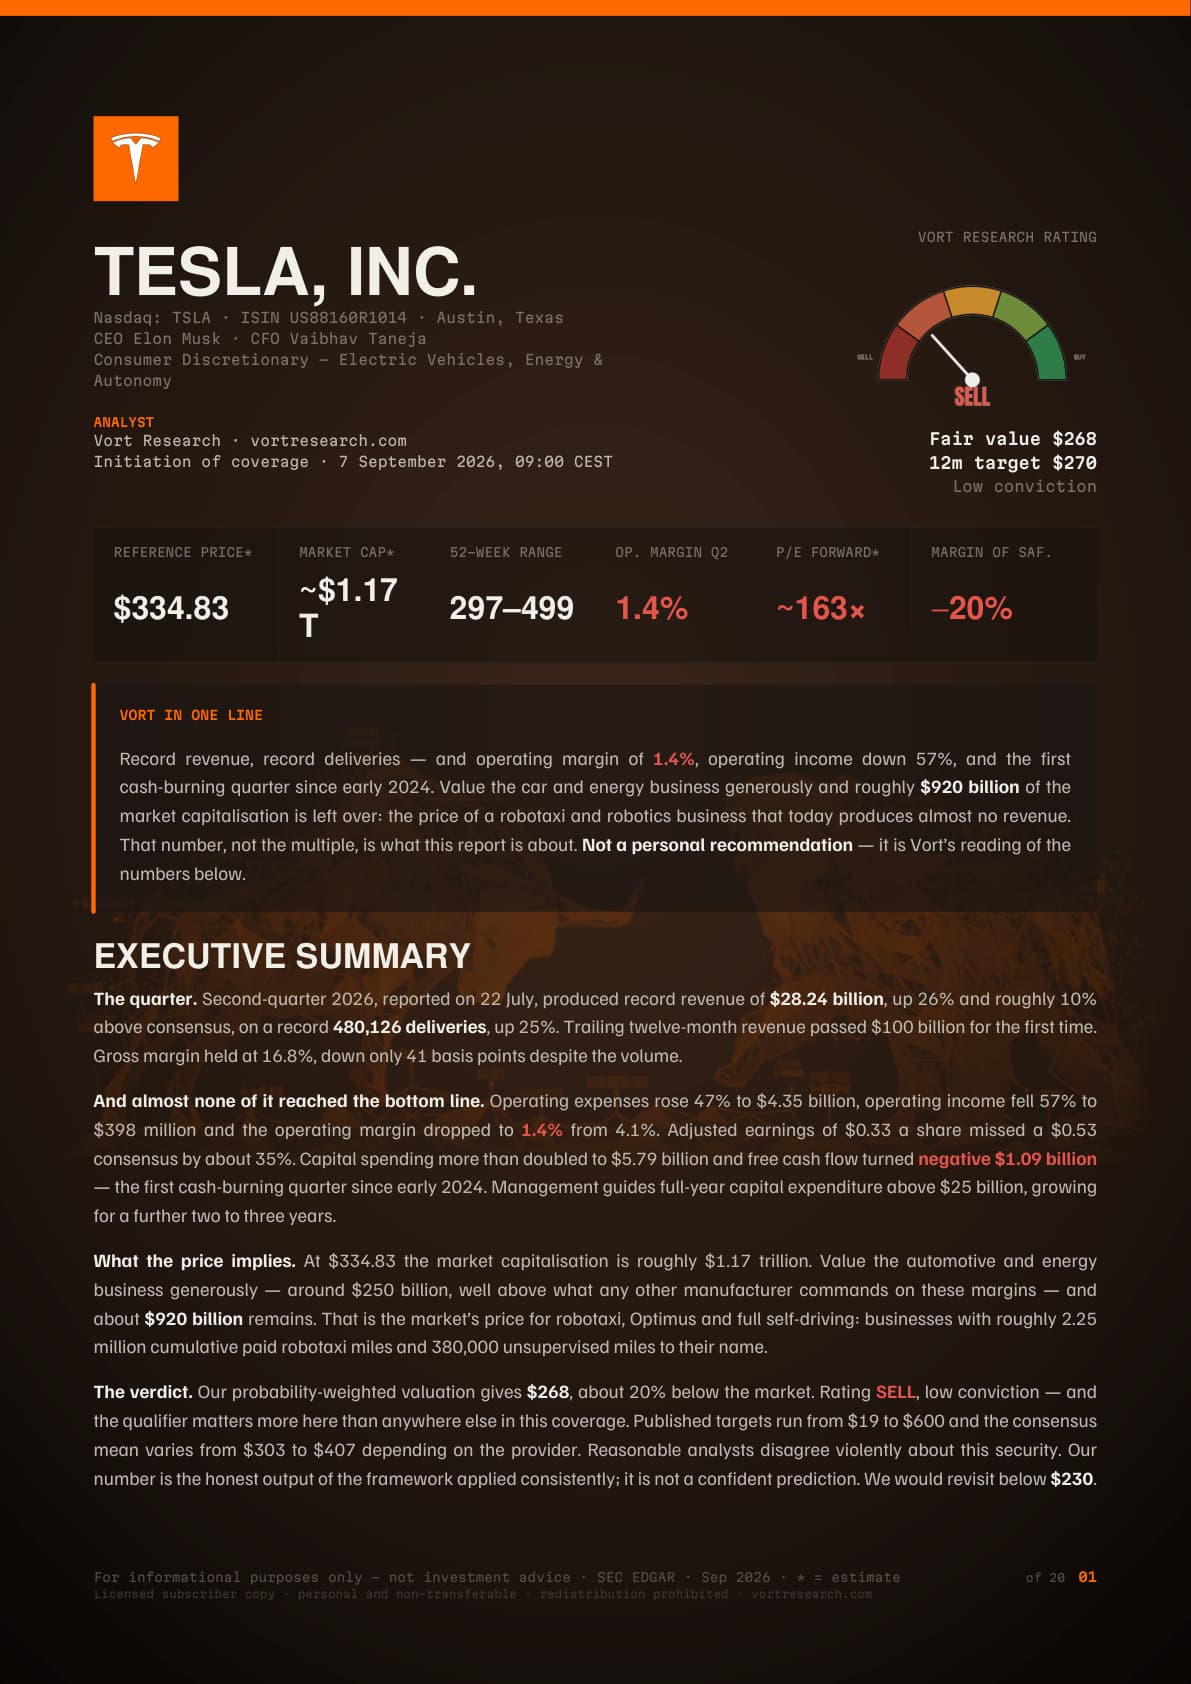
A record quarter, and a trillion-dollar question
Record revenue, record deliveries — and an operating margin of 1.4%, operating income down 57%, and the first cash-burning quarter since early 2024. Value the car and energy business generously and roughly $920 billion of the market capitalisation is left over: the price of a robotaxi and robotics business that today produces almost no revenue. That number, not the multiple, is what this report is about.
▼ Variazione sulla chiusura precedente: -1,29% (-4,72 USD)
Potenziale al fair value
-26%
dall’ultima chiusura
334,83 USD al report268 USD fair value
Il mercato USA è chiuso: il prezzo è quello di chiusura del 15 ottobre 2026. In seduta la quotazione è differita fino a 15 minuti. Il fair value è quello del report del 7 settembre 2026 e non si aggiorna con il mercato. Vort Research fornisce contenuti informativi ed educativi. Non è consulenza finanziaria personalizzata né sollecitazione all’investimento.
Il report completo è riservato agli abbonati Vort+.
Giudizio, fair value e ragionamento di questa pagina sono pubblici. Il PDF e le slide si scaricano con Vort+; se ce l’hai già, accedi.
Revenue of $28.24 billion and 480,126 deliveries were both records, and gross margin held at 16.8%. Then operating expenses rose 47% and operating income fell 57% to $398 million — a 1.4% operating margin. Both facts describe the same three months.
Roughly $920 billion of the price is for businesses that barely exist yet.
Value the car and energy business as generously as the numbers allow — an 8% margin, six times what was just reported, on a 35× multiple — and it reaches about $250 billion. The rest of the $1.17 trillion is the market's price for robotaxi, Optimus and full self-driving.
The one number that would settle it has never been published.
Tesla discloses robotaxi miles, cities and safety — 2.25 million cumulative paid miles, 380,000 unsupervised, zero notable incidents. It has never disclosed revenue, cost or margin per mile. No analyst can model that business, including us.
operating margin, Q2
1.4%
operating income
−57%
implied value of autonomy
~$920bn
cumulative paid robotaxi miles
2.25m
I conti in sintesi
Second quarter 2026, reported 22 July
Revenue Q2 2026
$28.24bn
↗ in aumento: +26%
Deliveries
480,126
↗ in aumento: +25%
Gross margin
16.8%
↘ in calo: −41bps
Operating income
$398m
↘ in calo: −57%
Operating margin
1.4%
↘ in calo: −2.7pp
Operating expenses
$4.35bn
↘ in calo: +47%
Capital expenditure
$5.79bn
↘ in calo: +142%
Free cash flow
−$1.09bn
↘ in calo: first burn since 2024
L’analisi
Sintesi gratuita
The damage is below the gross margin line
Gross margin held at 16.8% on record volume — the market had feared a discount-driven collapse and did not get one. What jumped was operating expense: +47% to $4.35 billion on artificial intelligence, Optimus, robotaxi and the chief executive's pay package. The car business is funding an expansion into two categories with no revenue.
What the price implies, worked backwards
At $334.83 on roughly 3.5 billion shares the market capitalisation is about $1.17 trillion. Every assumption we set in Tesla's favour still values the automotive and energy business at only ~$250 billion. That leaves ~$922 billion — larger than all but a handful of companies on earth — as the price of businesses with no disclosed economics.
The spending is a choice, and it lasts years
Capital expenditure more than doubled to $5.79 billion in one quarter and free cash flow turned negative $1.09 billion. Guidance is above $25 billion for the full year, growing for two to three more. A shareholder is funding an option, and the premium is paid quarterly.
Tesla is not an automotive investment at this price; it is a position on autonomy with a car company attached.
Vort Research — Tesla initiation, 7 September 2026
Cosa fa, e come guadagna
Il mestiere
Tesla makes electric vehicles, energy storage systems and — increasingly — bets. It sells roughly two million cars a year, operates a fast-growing energy storage business, and is spending heavily to build two things that do not yet meaningfully exist as businesses: an autonomous ride-hailing network and a humanoid robot.
Da dove vengono i ricavi
Automotive — Model 3, Y, S, X, Cybertruck480,126 in Q2
Energy — grid and residential storagegrowing fast
Robotaxi, Cybercab, Optimuspre-revenue
Il modello
Two businesses generate the cash and three consume it. That division is the whole company at present, and it is why record deliveries produced a 1.4% operating margin.
Il giudizio Vort in quattro voci
È una sintesi qualitativa e non è una raccomandazione.
Demand
✓Answered
Record revenue and record deliveries. The question of whether people still buy the cars is settled.
Unit economics
✓Intact
Gross margin held at 16.8% on record volume — Tesla sold more without destroying the margin on each one.
Profitability
×Collapsed
1.4% operating margin, income −57%, first cash burn since early 2024. Deliberate, but real.
Valuation
×Unanchored
~$920bn rests on businesses whose revenue, cost and margin per mile have never been published.
Con chi compete
Società
Dove compete
TeslaQuesto titolo
Electric vehicles, energy, and an autonomy option
BYD
Outsells Tesla globally and competes on cost
Waymo (Alphabet)
Autonomous ride-hailing, multi-sensor, further ahead
Chinese domestic makers
Price and feature pressure at home and in emerging markets
Legacy manufacturers
Slower on electric vehicles, but present
Regulation replaces substitutes as the fifth force, and for the autonomy business it is the binding constraint: robotaxi expansion is a city-by-city permission process, and no amount of engineering progress removes it.
Come lo valutiamo
Il numero e il ragionamento
Fair value Vort
$268
No multiple on current earnings produces a number worth writing down — 323 times trailing earnings is arithmetically true and analytically empty. Tesla is valued here as two things: an automotive and energy business on normalised earnings, plus an autonomy option priced explicitly in each scenario. Probability-weighted across $71 bear, $186 base and $650 bull, that gives $268 against a price of $334.83 — about −20%. We would revisit below $230.
Multipli
P/E trailing
~323×
P/E forward
~163×
Auto & energy value
~$250bn
Implied autonomy value
~$922bn
Cosa può andare storto
4 rischi, in ordine
01Autonomy proves worth less than the price implies
Medium probability, very high severity. The whole disagreement with the market sits on one line: we underwrite about $690 billion of autonomy value, the price implies about $920 billion.
02Capital expenditure stays above $25bn
High probability. Two to three more years at that level, against $398 million of quarterly operating income, means the cash flow statement looks like this for a while.
03Regulatory delay to robotaxi expansion
Permission is granted city by city and state by state, and it can be withdrawn faster than it was granted.
04A serious autonomous safety incident
Low probability, very high severity — the one risk here that could revalue the security in a single day. The zero-incident record is an asset, and it is fragile.
In conclusione
La sintesi gratuita finisce qui
Dove ci posizioniamo
SELL
Fair value $268, 12-month target $270, low conviction — and the qualifier matters more here than anywhere else in this coverage. Published targets run from $19 to $600 and consensus means vary from $303 to $407 depending on the provider: reasonable analysts disagree violently about this security. We are not arguing autonomy is worthless; we are declining to pay the last quarter of the way. A reader who assigns higher odds to autonomy should reach a different conclusion, and would be reasoning correctly. We would revisit below $230.