Milano––:––apertachiusa. Orario regolare di contrattazione, con le festività di ciascuna borsa: quelle di Borsa Italiana per Milano, quelle del NYSE per New York.
New York––:––apertachiusa. Orario regolare di contrattazione, con le festività di ciascuna borsa: quelle di Borsa Italiana per Milano, quelle del NYSE per New York.
Critical Digital Infrastructure — Power & Thermal for Data Centres
The picks and shovels of AI, one layer below the optics
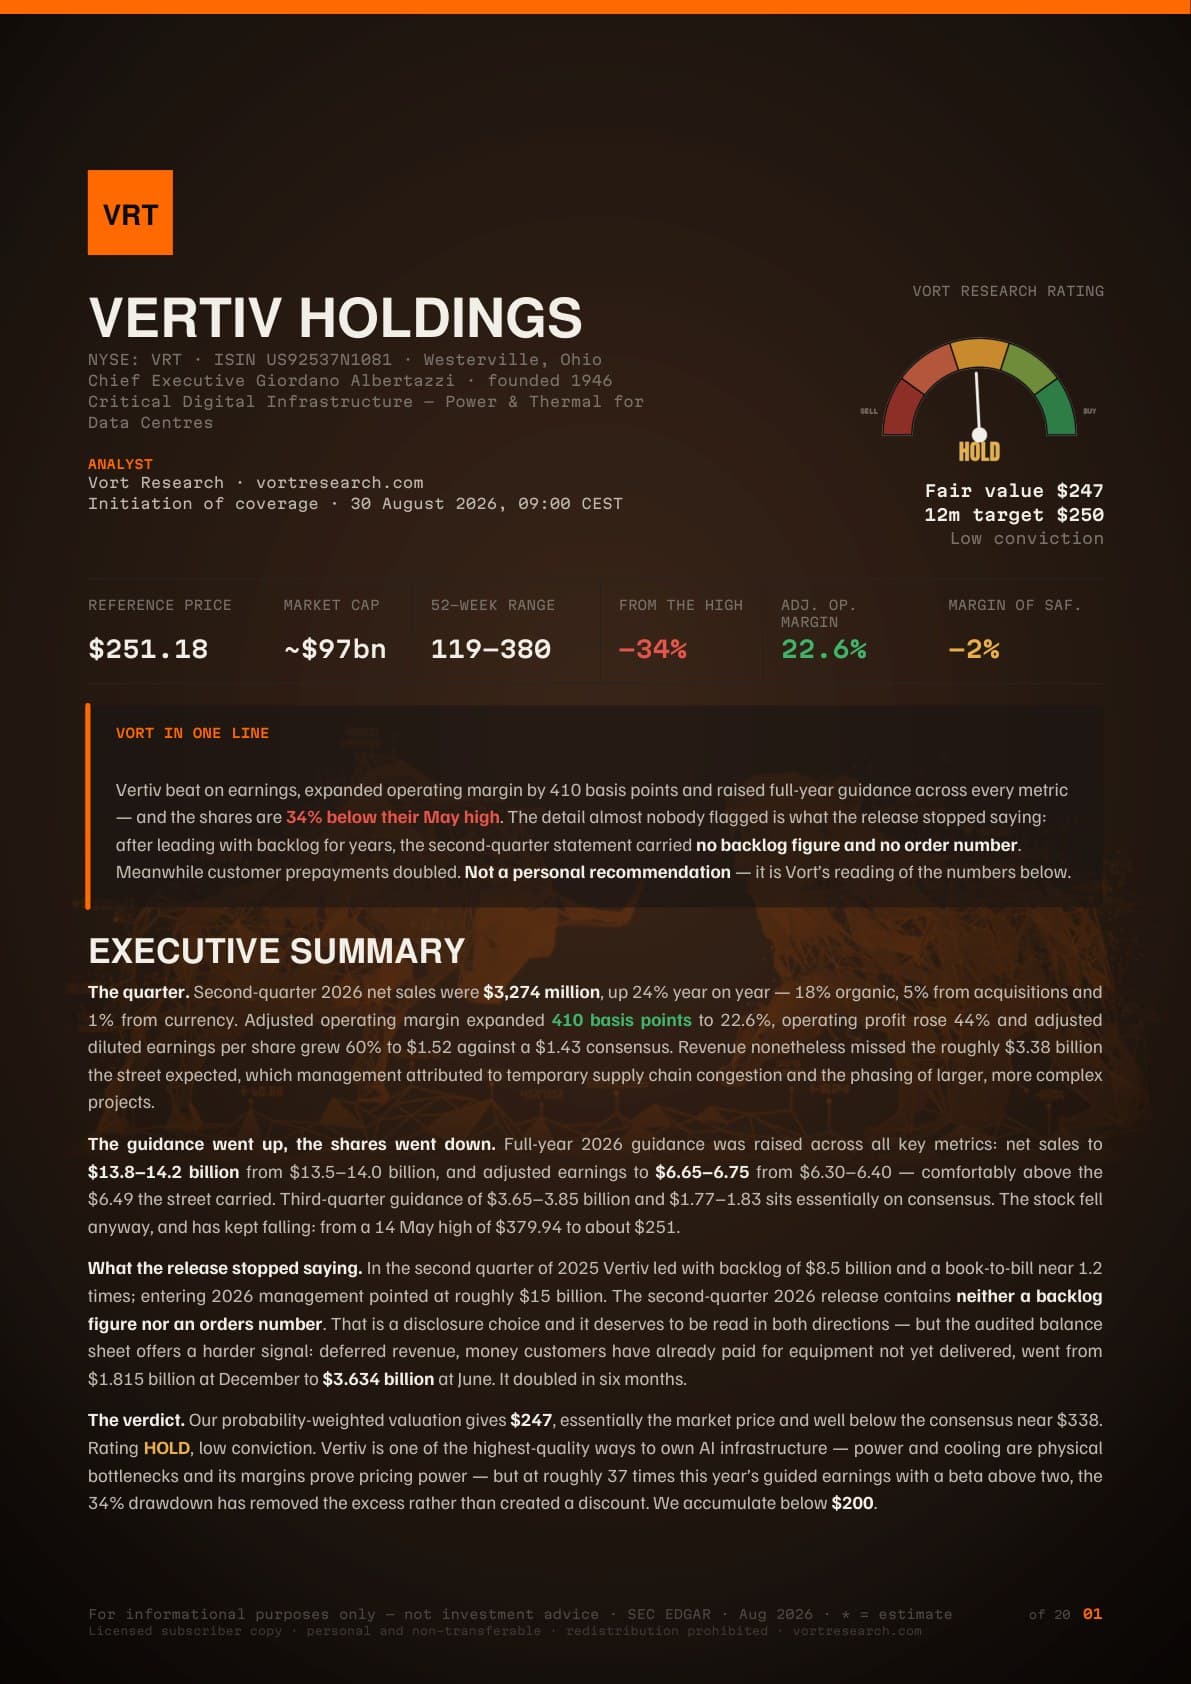
Vertiv beat on earnings, expanded operating margin by 410 basis points and raised full-year guidance across every metric — and the shares are 34% below their May high. The detail almost nobody flagged is what the release stopped saying: after leading with backlog for years, the second-quarter statement carried no backlog figure and no order number.
▼ Variazione sulla chiusura precedente: -3,63% (-8,08 USD)
Potenziale al fair value
+15%
dall’ultima chiusura
Obiettivo raggiunto. Il prezzo di mercato è sceso fino al fair value indicato nel report del 30 agosto 2026. Il giudizio resta quello del documento: un obiettivo centrato non è una nuova raccomandazione.
Il mercato USA è chiuso: il prezzo è quello di chiusura del 15 ottobre 2026. In seduta la quotazione è differita fino a 15 minuti. Il fair value è quello del report del 30 agosto 2026 e non si aggiorna con il mercato. Vort Research fornisce contenuti informativi ed educativi. Non è consulenza finanziaria personalizzata né sollecitazione all’investimento.
Il report completo è riservato agli abbonati Vort+.
Giudizio, fair value e ragionamento di questa pagina sono pubblici. Il PDF e le slide si scaricano con Vort+; se ce l’hai già, accedi.
Margin expansion that hardware companies do not usually deliver.
Adjusted operating margin expanded 410 basis points in twelve months to 22.6% while revenue grew 24%. Liquid cooling and high-density power carry more content per megawatt than the equipment they replace, and the customers deploying them are working against deadlines rather than shopping on price.
The balance sheet is harder evidence than the press release.
Deferred revenue — money already received for equipment not yet delivered — doubled from $1.815 billion to $3.634 billion in six months. Customers do not prepay for equipment they are not expecting to take.
The disclosure that disappeared.
For years Vertiv led its quarterly release with backlog. The second-quarter 2026 release contains no backlog figure and no orders number at all. Companies headline a metric when it is growing and go quiet when it is not.
operating margin expansion
+410bps
adjusted operating margin, Q2
22.6%
deferred revenue (doubled in 6 months)
$3.63bn
P/E on FY26 guidance
~37×
I conti in sintesi
Second quarter 2026, reported 29 July
Revenue Q2 2026
$3,274m
↗ in aumento: +24%
FY26 guidance
$13.8–14.2bn
↗ in aumento: raised
Adjusted EPS Q2
$1.52
↗ in aumento: +60%
FY26 adjusted EPS
$6.65–6.75
↗ in aumento: raised
Deferred revenue
$3.634bn
↗ in aumento: +100%
Return on equity
43.9%
Gross margin (TTM)
38.0%
Capex / revenue
~4%
L’analisi
Sintesi gratuita
The disclosure that disappeared
For years Vertiv led its quarterly release with backlog. The Q2 2026 release contains no backlog figure and no orders number. The bearish reading is obvious; the bullish counter is that deferred revenue doubled to $3.63bn — audited balance-sheet cash, not a management-defined metric.
Power and cooling are the binding constraint
Data centre construction today is limited by megawatts and heat rejection, not by chips. Substitutes is the most favourable Porter force: a data centre cannot decide to do without power or cooling. That is a stronger structural position than any component supplier in the AI chain.
At 37 times there is no room for error
The 34% drawdown removed a large premium — the same company traded at fifty times in May. Our judgement is that it has removed the excess rather than created a discount. The disagreement with consensus is almost entirely in the multiple, not in the earnings.
Companies headline a metric when it is growing and go quiet when it is not.
Vort Research — Vertiv initiation, 30 August 2026
Cosa fa, e come guadagna
Il mestiere
Vertiv keeps data centres running and cool. Power management, switchgear, busbar, uninterruptible supplies, energy storage — and, increasingly, the thermal systems that make dense AI racks physically possible, including liquid cooling. The company traces to 1946 and now does business in more than 130 countries.
Da dove vengono i ricavi
Thermal management (air and liquid cooling)growing fastest
Power management (AC/DC, switchgear, UPS)high content/MW
Services, integrated modular, energy storagerecurring
Il modello
Capital-intensive manufacturing into a market where supply, not demand, sets the price. Five plant expansions under way; ThermoKey adds European heat rejection capacity.
Il giudizio Vort in quattro voci
È una sintesi qualitativa e non è una raccomandazione.
Business
✓Strong
Power and cooling are the physical constraint on AI infrastructure, with no substitutes.
Accounts
✓Strong
Margin +410bps, ROE 43.9%, deferred revenue doubled. Real pricing power.
Valuation
±Fairly priced
At ~37× guided earnings the drawdown removed the excess, not created a discount.
Disclosure
×Concerning
Backlog and orders withheld from Q2 release; revenue missed on timing for a second quarter.
Con chi compete
Società
Dove compete
Vertiv HoldingsQuesto titolo
Power and cooling for data centres — the picks and shovels
Schneider Electric
Full-stack power and cooling, larger and broader
Eaton
Direct overlap in electrical power management
ABB
Strong in medium voltage electrification
nVent, Munters
Narrower thermal and enclosures specialists
The competitive matrix is real but the substitutes force is close to zero: a data centre cannot decide to do without power or cooling. That is why margin expanded 410 basis points.
Come lo valutiamo
Il numero e il ragionamento
Fair value Vort
$247
A probability-weighted valuation across scenarios running from $158 to $353, against a price of $251.18 — about −2%. The 12-month target is $250. The disagreement with consensus is almost entirely in the multiple: we model within 2% on earnings and eight turns lower on what they are worth. We accumulate below $200.
Multipli
P/E on FY26 guidance
~37×
Forward P/E (NTM)
~32×
P/E trailing
~60×
EV / Revenue FY26E
~7×
Cosa può andare storto
4 rischi, in ordine
01Revenue timing slips again in Q3
A third consecutive quarter of revenue below expectation on timing would move the explanation from phasing to demand or capability. Any single thesis-breaker moves the rating to SELL.
02Backlog remains undisclosed
If the October release still carries no backlog figure, the market will read it as confirmation that orders have peaked.
03Hyperscaler capex pauses
The cloud capex commitments underpin demand. A named hyperscaler publicly deferring construction would reset the sector multiple, not just this company.
04Extreme share price volatility
Beta 2.08 and a 52-week range from $118.70 to $379.94 — a factor of more than three. Position sizing matters as much as direction.
In conclusione
La sintesi gratuita finisce qui
Dove ci posizioniamo
HOLD
Fair value $247, 12-month target $250, low conviction. The business is not in question: operating margin expanded 410 basis points, deferred revenue doubled and power and cooling are the physical constraint on AI infrastructure. What is in question is whether the backlog disclosure disappeared because orders peaked, and whether the revenue timing miss is phasing or something else. We accumulate below $200.