Milano––:––apertachiusa. Orario regolare di contrattazione, con le festività di ciascuna borsa: quelle di Borsa Italiana per Milano, quelle del NYSE per New York.
New York––:––apertachiusa. Orario regolare di contrattazione, con le festività di ciascuna borsa: quelle di Borsa Italiana per Milano, quelle del NYSE per New York.
Utilities — Independent Power Production & Retail Energy
Everything the bull case asked for arrived, and the stock fell a third
Adjusted EBITDA up 30%, generation earnings up 68%, and the shares 32% below their high. The sell-off followed a revenue line that missed by 36% — a figure that, for a producer with 100% of 2026 output already sold forward, describes the hedge book rather than the business.
▲ Variazione sulla chiusura precedente: +1,57% (+2,38 USD)
Potenziale al fair value
+18%
dall’ultima chiusura
149,79 USD al report182 USD fair value
Il mercato USA è chiuso: il prezzo è quello di chiusura del 15 ottobre 2026. In seduta la quotazione è differita fino a 15 minuti. Il fair value è quello del report del 7 settembre 2026 e non si aggiorna con il mercato. Vort Research fornisce contenuti informativi ed educativi. Non è consulenza finanziaria personalizzata né sollecitazione all’investimento.
Il report completo è riservato agli abbonati Vort+.
Giudizio, fair value e ragionamento di questa pagina sono pubblici. Il PDF e le slide si scaricano con Vort+; se ce l’hai già, accedi.
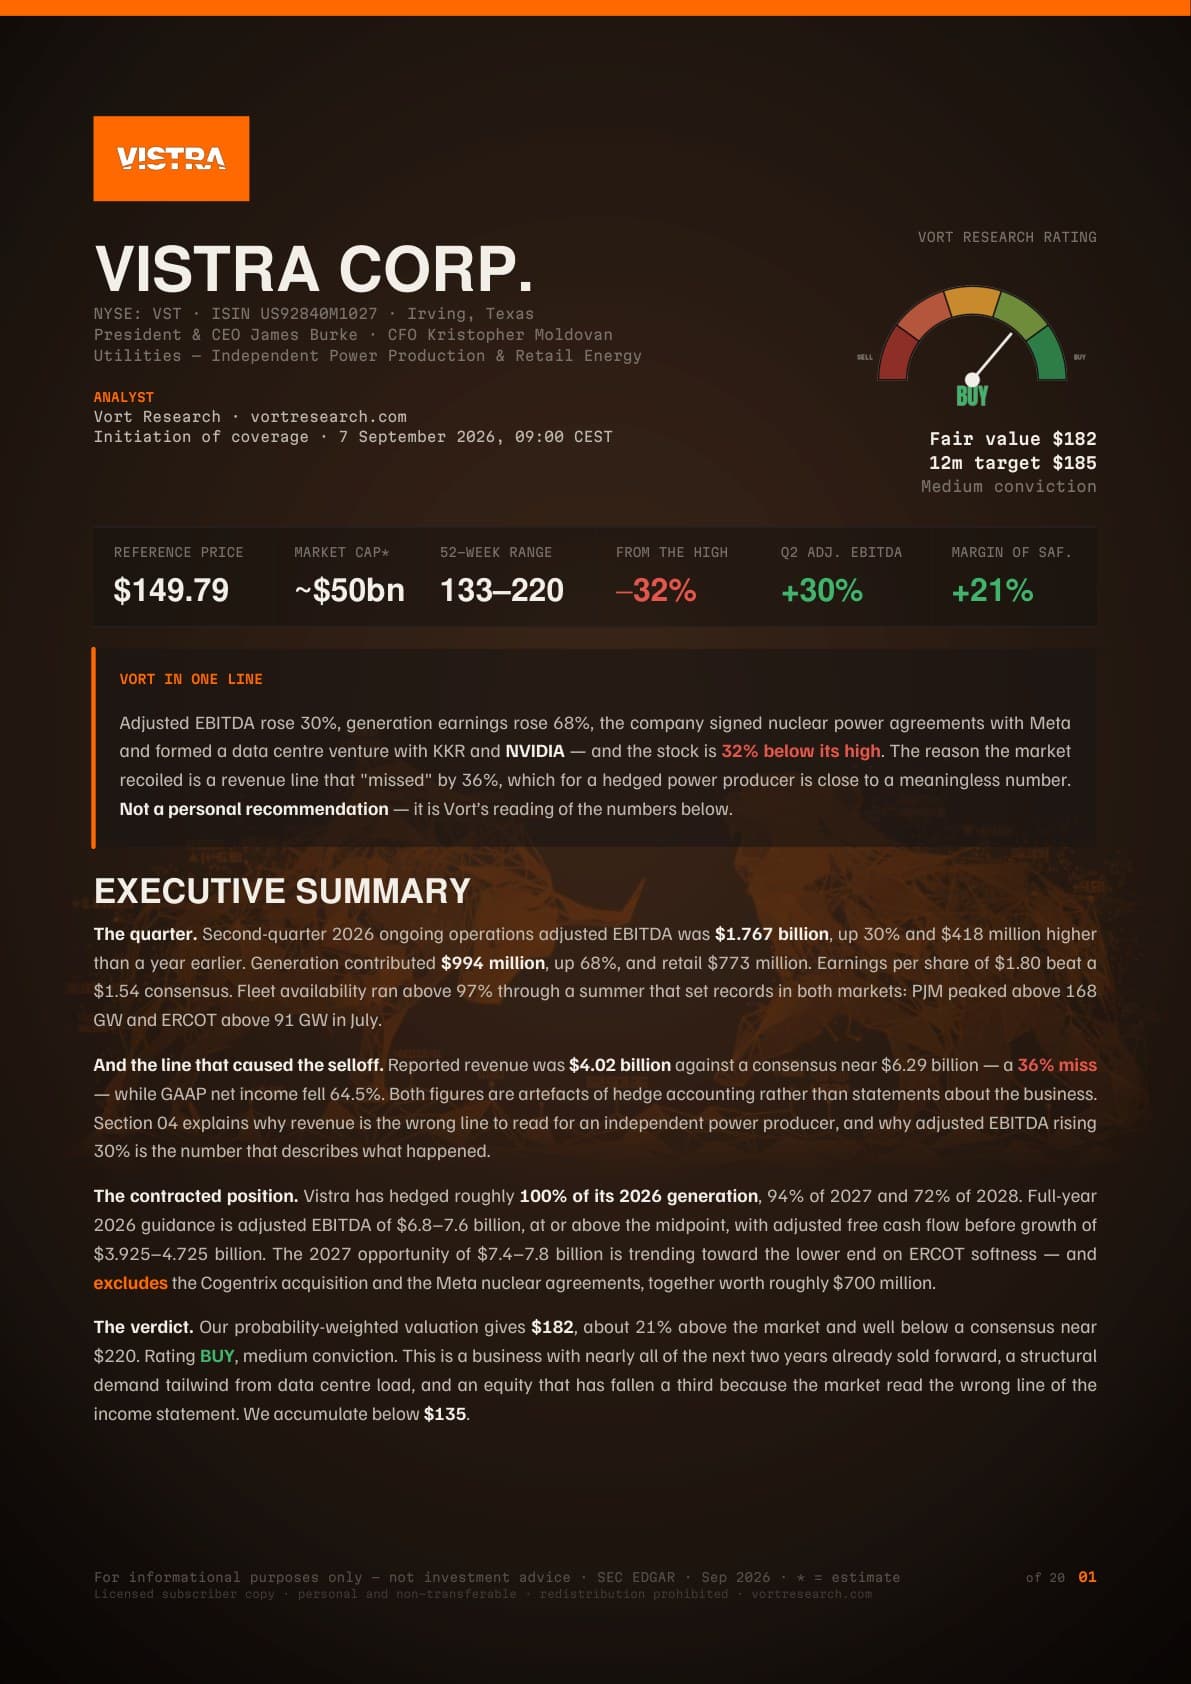
Second-quarter adjusted EBITDA was $1.767bn, up 30% and $418m higher than a year earlier. Generation contributed $994m, up 68%, retail $773m, and earnings per share of $1.80 beat a $1.54 consensus. The fleet ran above 97% availability through a summer that set records in both markets — PJM peaked above 168 GW and ERCOT above 91 GW in July. The stock is $149.79, −32% from its high.
Revenue is close to a meaningless line for a hedged power producer.
Reported revenue was $4.02bn against a consensus near $6.29bn — a 36% miss — and GAAP net income fell 64.5%. Both move with unrealised mark-to-market on the hedge book: when forward prices shift, so does the value of contracts already signed, though no electricity has been generated and no cash has changed hands. Neither line appears anywhere in our valuation, which works from 2028 adjusted EBITDA against an enterprise multiple with roughly $26bn of estimated net debt deducted.
Two years are already sold, and ~$700m sits outside the guidance.
Vistra has hedged about 100% of its 2026 generation, 94% of 2027 and 72% of 2028, so the prices that set the next two years of earnings have been agreed. FY2026 guidance is adjusted EBITDA of $6.8–7.6bn with adjusted free cash flow before growth of $3.925–4.725bn; the 2027 range of $7.4–7.8bn is trending to the lower end on ERCOT softness and excludes Cogentrix and the Meta nuclear agreements, worth roughly $700m together — nine to ten per cent of that year's EBITDA. The genuine risk is 2028, where 28% of the book is still open and ERCOT forwards have softened on battery additions.
adjusted EBITDA, Q2
+30%
generation earnings
+68%
revenue against consensus
−36%
of 2027 output already hedged
94%
I conti in sintesi
Second quarter 2026, reported 7 August
Adjusted EBITDA Q2 2026
$1.767bn
↗ in aumento: +30%
Generation EBITDA
$994m
↗ in aumento: +68%
Retail EBITDA
$773m
the hedge against generation
Earnings per share
$1.80
↗ in aumento: beat $1.54
Reported revenue
$4.02bn
↘ in calo: −36% vs consensus
GAAP net income
—
↘ in calo: −64.5%
Fleet availability
>97%
↗ in aumento: through record summer peaks
FY2026 adjusted EBITDA guidance
$6.8–7.6bn
↗ in aumento: ~+27%
L’analisi
Sintesi gratuita
Revenue is the wrong line for a power producer
Neither the revenue line nor GAAP net income describes the quarter. A generator that has sold its output forward marks those contracts to market every quarter, so when forward prices move the unrealised value of the hedge book moves through revenue and through net income, with no electricity generated and no cash changing hands — though the disclosure never decomposes the gap between unrealised marks and realised volumes. Adjusted EBITDA from ongoing operations rose 30% to $1.767bn, generation earnings rose 68% to $994m, and the fleet ran above 97% availability through record July peaks in both markets. Our valuation uses neither reported revenue nor GAAP net income anywhere, just as a bank cannot be valued on enterprise value: in both cases the standard industrial template measures the wrong thing.
Two of the next three years are already sold
Roughly 100% of 2026 generation is hedged, 94% of 2027 and 72% of 2028, so the prices that set those years have been agreed. The soft ERCOT forward curve, which has already trimmed the 2027 range toward its lower end, does the bulk of its damage in 2028 rather than in the years the market is discounting. That is why guidance of $6.8–7.6bn for 2026 is credible, and why the conviction here is medium rather than low. What is genuinely open is the remaining 28% of the 2028 book — at what price it gets filled, and whether battery additions keep flattening the Texas price curve.
The demand story, and the ~$700m outside guidance
American electricity demand is growing again after two decades of flatness, and Vistra owns dispatchable capacity in the two markets where that is clearest: ERCOT, forecast at 4–6% a year to 2030, and PJM at 2–3%. Both set consumption records in July — PJM above 168 GW, ERCOT above 91 GW. The Meta agreements contract existing nuclear output to a hyperscaler at agreed prices, and Helix Digital Infrastructure — formed with KKR, NVIDIA and the Kuwait Investment Authority, with a commitment of up to $1.0bn — positions Vistra as a preferred power partner for data centre developers on a rack-to-grid basis. It is early and small. Neither Cogentrix nor the Meta agreements is in the 2027 guidance, and management puts the two together at roughly $700m — nine to ten per cent of a $7.4–7.8bn range, sitting outside the number the market is valuing. What we cannot model is how fast that load actually arrives: the growth forecasts imply it tightens ERCOT from 2028, and the forward curve does not yet show it.
A buyer at this price is not taking power price risk for two years — they are taking it in the third, which is a materially different proposition from what the share price move implies.
Vort Research — Vistra initiation, 7 September 2026
Cosa fa, e come guadagna
Il mestiere
Vistra generates electricity and sells it. It owns one of the largest generation fleets in the United States — nuclear, gas, coal and a growing battery portfolio — concentrated in ERCOT, the Texas market, and PJM, the largest wholesale market in the country. It also owns a retail energy business that sells power directly to households and companies. Those two halves are the company: the retail book hedges the generation book, which is why the segments have to be read together rather than one at a time.
Da dove vengono i ricavi
Generation — nuclear, gas, coal and batteries$994m in Q2, +68%
Retail — power sold to homes and businesses$773m in Q2
Cogentrix — acquired gas fleet, FERC approvedoutside 2027 guidance
Helix — data centre venture with KKR, NVIDIA and KIAup to $1.0bn committed
Il modello
A pure generator is a leveraged bet on wholesale prices; a pure retailer is short power and gets hurt when prices spike. Vistra is both, so a move in the wholesale price largely offsets itself between the two segments — and that is what lets the company sell nearly all of its output forward two years ahead and still guide to growth.
Il giudizio Vort in quattro voci
È una sintesi qualitativa e non è una raccomandazione.
Operations
✓Delivered
Adjusted EBITDA $1.767bn, +30%, with generation $994m, +68%. Fleet availability held above 97% through July peaks of more than 168 GW in PJM and 91 GW in ERCOT.
Visibility
✓Contracted
~100% of 2026 generation is hedged and 94% of 2027. The uncertainty is not what Vistra earns in 2026 or 2027 — it is the price at which the open 28% of 2028 gets sold.
Power prices
×Soft
ERCOT forwards have weakened as batteries were added, pushing the 2027 opportunity of $7.4–7.8bn toward the lower end. It bites on the 28% of 2028 still open, and we cannot forecast where that book gets filled.
Leverage
×Amplifying
We estimate net debt near $26bn against $50bn of equity value, and it is deducted before the equity is divided out. One turn of multiple on $8.5bn of EBITDA moves fair value about $25 a share — which is how a company with 94% of next year sold forward still falls a third.
Con chi compete
Società
Dove compete
VistraQuesto titolo
Generation and retail together in ERCOT and PJM, sold forward two years out
Constellation Energy
Nuclear fleet and hyperscaler contracts — the closest listed comparable
NRG Energy
The same integrated model in the same two markets
Battery developers
Adding storage to ERCOT fast enough to flatten the price spikes
Regulated utilities
Competing for the same data centre load, with a rate base behind them
Regulation replaces substitutes as the decisive force, and it scores 4.0 out of 5 in our reading — capacity market design, interconnection queues, emissions rules and the treatment of co-located data centre load are all decided outside the company and move earnings directly. New entrants is the mildest force at 2.0, because building generation takes years and the interconnection queue takes years more, which is precisely what makes an existing fleet valuable. The live competitive change is not a rival producer but batteries: they are being added to the Texas grid fast enough to flatten the price spikes that used to reward dispatchable plant, and that is structural rather than cyclical.
Come lo valutiamo
Il numero e il ragionamento
Fair value Vort
$182
Vistra is valued on 2028 adjusted EBITDA times an enterprise multiple, with roughly $26bn of estimated net debt deducted — derived from published EV/EBITDA rather than the balance sheet — and the result divided by about 334.5m shares. Three scenarios carry the number: bear, $7.5bn of EBITDA at 8.5×, gives $114; base, $8.5bn at 10.5×, gives $190; bull, $9.5bn at 12.0×, gives $264 — weighted 30 / 50 / 20. That produces $182, about 21% above the $149.79 reference price and 17% below a consensus near $220. The bridge from the market price runs the same way: +$46 for the 94% of 2027 output already sold forward, +$29 for Cogentrix and the Meta agreements, then −$27 for ERCOT softness and −$16 for leverage and capital expenditure. We take the lower end of management's own 2027 range of $7.4bn to $7.8bn because management said to, and we apply 10.5× where the street applies about 12× — the two compound. We accumulate below $135, about 18% above the $114 bear case.
Multipli
EV / 2026E adjusted EBITDA
~10.5×
EV / 2027E adjusted EBITDA
~10.1×
EV / 2027E incl. Cogentrix
~9.2×
P/E trailing
~25.2×
Cosa può andare storto
4 rischi, in ordine
01Cogentrix and the Meta agreements do not land as guided
Medium probability, high severity. The ~$700m excluded from guidance is +$29 of our $32 bridge and nine to ten per cent of 2027 EBITDA; cancellation or material delay removes it outright. The February 2027 guidance is the first to include them, and is where this is settled.
02The open 28% of the 2028 hedge book fills at poor prices
Medium probability, very high severity. Battery additions have already pushed the Texas forward curve down, and the price at which the rest of 2028 is sold is precisely what the equity has been discounting — a rising hedge percentage alongside falling realised prices would turn the bear case into the base case.
03Data centre load arrives more slowly than forecast
Medium probability, high severity. The $264 bull case requires that load to tighten ERCOT from 2028, and it has not yet shown up in forward prices; the interconnection queue is the honest place to check, and a deferred hyperscaler commitment would put the shares at $125 to $145.
04Leverage amplifies every shortfall
Certain, high severity. Roughly $26bn of estimated net debt against $50bn of equity value means a modest disappointment in EBITDA reaches the share price magnified — the scenario span of $114 to $264 reflects the capital structure as much as the power market.
In conclusione
La sintesi gratuita finisce qui
Dove ci posizioniamo
BUY
Fair value $182, 12-month target $185, medium conviction. Vistra has sold forward 100% of its 2026 generation and 94% of 2027, owns dispatchable capacity in the two American markets where electricity demand is growing fastest, and carries roughly $700m of Cogentrix and Meta earnings outside its own guidance. The shares are 32% below their high because forward power prices softened and because a revenue line full of unrealised derivative marks came in 36% under consensus — in the same quarter adjusted EBITDA rose 30% and generation earnings rose 68%. For this to be wrong, ERCOT would have to stay soft long enough for the open 28% of the 2028 book to be contracted cheaply, and $26bn of net debt would turn that shortfall into a much larger move in the equity. It would also be wrong if the Meta agreements were cancelled or materially delayed, or if adjusted EBITDA fell below the guidance range — with 2026 fully hedged, that would be an operational failure rather than a price move, and a worse one. Medium conviction is the accurate label rather than a formality: the bear case is $114, published targets run from $106 to $313, and a reader who assigns lower odds to data centre load arriving on schedule should reach a smaller number and would be reasoning correctly. We accumulate below $135.